Steering Clear of Financial Traps: Common Mistakes in Frugal Living and Smart Spending
Go beyond simple penny-pinching. This guide reveals the hidden financial traps that even savvy savers fall into, from false economies and unrealistic budgets to lifestyle creep and investment mistakes. Learn to build true, lasting wealth by shifting from reactive saving to proactive, strategic spending.
By: Matheus Neiva on September 28, 2026
We’re often told that the path to financial freedom is paved with discipline and sacrifice. You diligently track your expenses, hunt for bargains, and cut back on luxuries, believing these frugal habits are the key to building wealth. But what if some of these ‘smart’ money moves are actually setting you back? It’s a frustrating paradox: despite your best efforts to save, you might find your financial goals remain stubbornly out of reach, leaving you to wonder what you’re doing wrong.
The reality is that effective financial management goes far beyond simple penny-pinching. In a world of volatile economic trends and constant social pressure to spend, the line between savvy saving and costly error has become incredibly fine. Many common financial traps are disguised as prudent choices, from buying the cheapest option that quickly fails to creating a budget so restrictive it’s destined for collapse. These subtle mistakes don’t just stall your progress; they can actively drain your resources in the form of replacement costs, missed opportunities, and mounting debt.
This guide steers you clear of those hidden pitfalls. We will dissect the most common mistakes people make in their pursuit of financial health, moving beyond the obvious advice. We’ll explore the illusion of false economies, the psychological traps of budgeting and lifestyle creep, the blunders new investors often make, and why ignoring the bigger economic picture can undermine your entire strategy. By the end, you’ll be equipped not just to save money, but to make smarter decisions that build genuine, resilient wealth over the long term.
The Illusion of Savings: When Frugality Backfires
Being frugal is often celebrated as a cornerstone of financial health, but there’s a fine line between smart saving and self-sabotage. What most people miss is that not all savings are created equal. Some seemingly clever shortcuts can end up costing you significantly more in money, time, and frustration down the road. It’s a classic case of winning the battle but losing the war.
This happens when we focus exclusively on the initial price tag instead of the total cost of ownership. The cheapest option is rarely the best value. Understanding this distinction is core to developing genuinely smarter spending habits that build wealth over time.
The ‘Buy Cheap, Buy Twice’ Trap
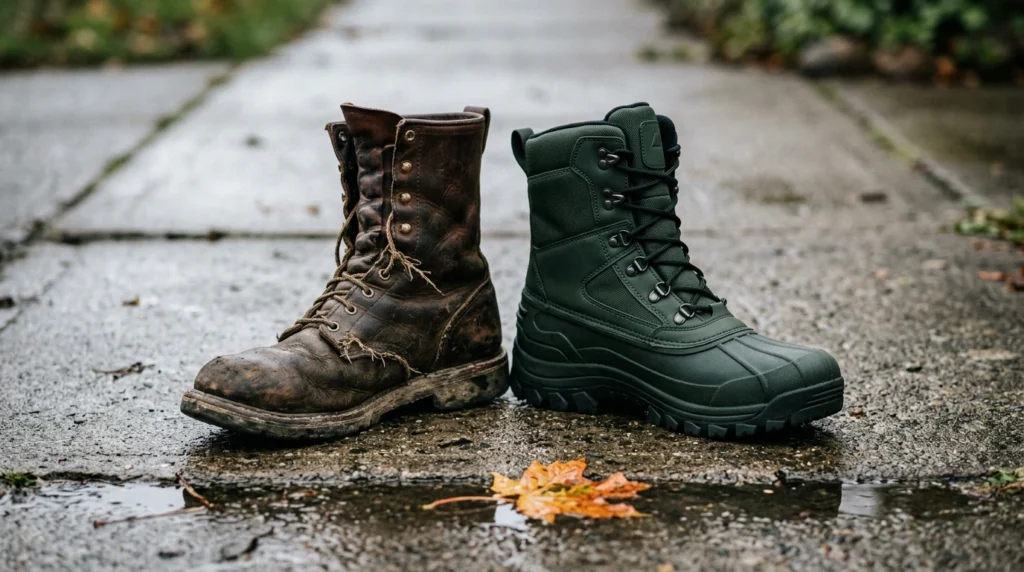
We’ve all heard the old adage, and for good reason. Opting for a low-quality item because of its tempting price often leads to a cycle of replacement. Think about a pair of $20 winter boots that fall apart after one season versus a $120 pair that lasts for five years or more. The cheap boots cost you $20 per year, while the quality pair costs $24 per year — a small difference for superior performance and reliability.
This principle applies to everything from kitchen gadgets to clothing and electronics. A report from Consumer Reports suggests that for certain appliance categories, models with higher initial costs had failure rates nearly 45% lower over a five-year period than their budget counterparts. The stress of an unexpected failure and the hassle of replacement also carry a non-financial cost. It’s like building a house with shoddy materials; the foundation might be cheap, but the constant repairs will drain your resources.
Here is a simple breakdown of how this plays out:
Item
Short-Term Saving
Long-Term Cost
Budget Office Chair
Saved $200 on initial purchase
Needs replacement in 2 years. Poor ergonomics lead to back pain (potential medical costs). Total 5-year cost: $500+.
Quality Office Chair
Spent $300 upfront
Lasts 10+ years with good support. Total 5-year cost (prorated): $150.
Cheap Kitchen Knife Set
Saved $80
Dulls quickly, needs frequent sharpening, breaks. Replaced after 18 months. Frustrating to use.
Quality Kitchen Knife Set
Spent $125 upfront
Stays sharp, lasts for decades with proper care. A joy to use.
Ignoring Maintenance and Longevity
Another common pitfall is skipping routine maintenance to save a few dollars. Postponing an oil change for your car, for example, might save you $75 today. But what happens when that neglect contributes to major engine damage costing thousands to repair? The initial saving becomes laughably insignificant in comparison to the eventual expense.
This applies to your home as well. According to the National Association of Home Builders, neglecting simple tasks like cleaning gutters can lead to water damage repairs costing an average of $2,386. These are not just inconvenient expenses; they are entirely avoidable ones that derail your financial goals. Effective smart spending strategies always account for the upkeep that preserves an asset’s value and function.
The True Cost of DIY Gone Wrong
The internet is full of tutorials that make home repairs look easy. While some DIY projects are great for saving money, overestimating your abilities can be a costly mistake. A simple attempt to fix a leaky faucet can quickly escalate into a full-blown plumbing disaster, requiring an emergency call-out and repairs far more expensive than the original plumber’s quote.
Before starting a project, you must honestly assess your skill level and the potential risks. Sometimes, paying a professional is the most frugal choice.
Opportunity Costs of Extreme Frugality
Time is a finite resource, yet in the pursuit of saving a few pennies, we often squander it. Driving 30 minutes across town to save $0.15 per gallon on gas or spending hours clipping coupons to save $7.83 at the grocery store might feel like a win. But is it really? If your time is worth more than the amount you save per hour, you are operating at a net loss.
This is the concept of opportunity cost — the value of what you give up when you choose one option over another. That time spent on extreme penny-pinching could be used to learn a new skill, start a side hustle, or simply rest and recharge. Focusing too much on minor savings can distract from bigger financial wins, a key insight for anyone exploring emerging trends in frugal living. The goal isn’t just to spend less, but to optimize your resources, including your valuable time.
Budgeting Blunders: Missteps in Tracking and Planning
Having a budget is one thing; having one that actually works is another entirely. Many well-intentioned financial plans fail not from a lack of effort, but from core design flaws that set you up for failure. It’s a common frustration. You create spreadsheets and set limits, yet the numbers just don’t cooperate at the end of the month.
Unrealistic Expectations and Burnout
One of the most frequent errors is creating a budget that’s more of an aspirational fantasy than a practical guide. Slashing your food budget by 70% or vowing to never buy a coffee again is the financial equivalent of a crash diet—it’s unsustainable and often leads to burnout. You might stick to it for a week or two, but the restriction fatigue builds until you abandon the plan altogether. A survey by the Financial Planning Association found that over a third of people who abandon their budget do so because they found it too restrictive.
The goal isn’t to live a life of complete deprivation. It’s about making conscious choices. A better approach is to make gradual, incremental changes. Think of it like training for a 5k race; you don’t start by running the full distance on day one. You build up slowly, allowing your habits (and your willpower) to strengthen over time. This is a core principle behind developing effective smart spending strategies that last.
The ‘Latte Factor’ and Neglected Micro-Spending
On the other end of the spectrum lies the danger of ignoring the small leaks. The “latte factor” describes how small, frequent, and seemingly insignificant purchases can collectively drain a huge amount from your bank account. It’s not just about the daily coffee—it’s the $2.99 app purchase, the extra streaming service you forgot you subscribed to, or the convenience store snack. These are the budget termites.
What most people miss is that these expenses are often emotional or habitual, making them difficult to spot without diligent tracking. Are you really using all four of those video streaming platforms? The data suggests—though not conclusively—that most households have at least two redundant subscriptions. The key is to make these costs visible, which is a vital first step in decoding your spending habits and taking back control.
Budgeting Best Practices to Avoid Common Mistakes
Be Realistic: Base your budget on your last three months of actual spending, not an idealized version. Find areas for a 10-15% cut, not a 50% slash.
Track Everything: Use an app or a simple notebook to log every single expense for at least one month. The visibility is often enough to change behavior.
Schedule Regular Check-ins: A budget isn’t a “set it and forget it” document. Review your spending and progress weekly or bi-weekly to make adjustments.
Build in Fun Money: Allocate a specific, guilt-free amount for discretionary spending. This prevents the feeling of deprivation and helps you stick to the plan.
Automate Your Goals: The most effective way to ensure you’re saving and investing is to automate transfers to your savings or investment accounts right after you get paid. This approach is central to smart spending for frugal living in any economy.
Ultimately, a successful budget isn’t a cage but a tool that gives you permission to spend in alignment with your true priorities.
The goal is a boring portfolio that lets you have an exciting life, not the other way around.
— David Chen, Financial Planner
Common Mistake
The Smarter Approach
False Frugality
Focus on total cost of ownership and long-term value, not just the initial price tag.
Unrealistic Budgeting
Create a flexible, realistic plan based on actual spending and include guilt-free ‘fun money’.
Trend-Chasing Investments
Adopt a diversified, long-term strategy using low-cost index funds and avoid emotional decisions.
Lifestyle Creep
Automate savings increases with every raise and intentionally align spending with long-term goals.
Ignoring Economic Trends
Stay informed about inflation and interest rates to proactively manage debt and adjust your strategy.
Investment Illusions: When Prudent Becomes Risky
Moving from a saving mindset to an investing one is a major step, but it often comes with a dangerous temptation: chasing trends. Many new investors, eager for quick returns, pour money into speculative assets they heard about online or from a friend—a classic rookie error. The data suggests this is a widespread issue; a recent analysis by Morningstar revealed that funds experiencing sudden, high-volume inflows often underperform market averages over the subsequent three years. This happens because by the time a stock is popular, the big gains have likely already been made.
Putting all your financial eggs in one basket is a recipe for disaster. But isn’t that just common sense? Surprisingly, many beginners fail to diversify, concentrating their capital in a handful of familiar company stocks (often their employer’s). This lack of diversification is like building a house with only one support beam; a single point of failure can bring everything down. Understanding the core principles of investment basics is not optional.
True wealth-building is rarely exciting.
As financial planner David Chen puts it, “The goal is a boring portfolio that lets you have an exciting life, not the other way around.” A disciplined, long-term strategy, which includes regular rebalancing and a focus on low-cost index funds, is a far more reliable path. These foundations of prudent investment protect you from the emotional highs and lows of market speculation and align your money with your actual life goals.
A worn, scuffed work boot standing next to a new, sturdy dark green winter boot on a cracked concrete sidewalk, illustrating the ‘buy cheap, buy twice’ trap in frugal living.
The Pitfalls of ‘Keeping Up’: Social Pressure and Spending
Few things can sabotage a budget faster than the unspoken pressure to match the spending of those around you. It’s a powerful, often subconscious, force fueled by social media feeds and casual conversations about new cars, exotic vacations, and home renovations. This desire to keep up with the Joneses isn’t just a quaint saying; it’s a significant financial trap.
The data suggests this is a widespread issue. A study by Schwab found that 35% of Americans who use social media are influenced by their friends’ posts to spend money they hadn’t planned on. It’s a quiet-but-constant comparison game. What most people miss is that the “Joneses” are often financing that lifestyle with debt, a detail conveniently left out of their vacation photos.
Lifestyle Creep: The Silent Budget Killer
One of the most insidious forms of social spending is lifestyle creep. It happens gradually, almost without notice. You get a raise, and suddenly your daily $3 coffee becomes a $6 latte. Your reliable sedan gets traded in for a slightly more expensive SUV with a higher monthly payment. Each individual upgrade seems minor and justifiable. You earned it, right?
Over time, these small increases compound, completely rewriting your baseline expenses. It’s like a leaky faucet; a single drip is insignificant, but the cumulative waste over a year is substantial. Suddenly, you’re earning more money than ever but have less to show for it in savings or investments. Reversing this trend requires intentionality and some disciplined spending strategies to get your budget back on track.
This is where your financial plan hits a wall.
Navigating Social Expectations Without Overspending
Managing social pressure doesn’t mean becoming a hermit. It’s about setting boundaries and redefining what social connection means to you. Instead of automatically saying yes to an expensive dinner invitation, why not suggest a more budget-friendly alternative like a potluck, a game night, or a hike? The goal is to spend time with people, not to spend money on them.
Being transparent about your financial goals can also be surprisingly effective. A simple “That sounds amazing, but it’s not in my budget right now as I’m saving for a down payment” is often met with understanding — and you might even inspire others to be more mindful of their own spending. It’s a core principle in any guide to smarter spending habits. It shifts the focus from consumption to shared experiences.
Ultimately, decoupling your self-worth from your spending patterns is the key. Your financial health depends less on the car you drive and more on the choices you make when no one is looking.
Ignoring Economic Signals: Missing the Bigger Picture
Living frugally isn’t just about clipping coupons or finding the best deals; it’s also about understanding the economic weather you’re flying into. Many people focus so intently on their personal budget that they miss major shifts in the broader economy. It’s like meticulously planning a road trip without ever checking the forecast for a hurricane. This oversight can quickly undo all your hard work.
Inflation is a perfect example. When the cost of living rises, your carefully planned $50 weekly grocery budget might suddenly only cover half of what it used to. What most people miss is how this affects debt. Higher interest rates, often used to combat inflation, make carrying a balance on credit cards or taking out new loans significantly more expensive. The data suggests this is a common trap; consumer credit card debt rose by over 15.3% during the last major economic downturn, according to reports from the Federal Reserve Bank of New York.
You have to stay informed.
Paying attention to these signals allows you to adjust your strategy proactively. For instance, knowing that interest rates are likely to climb could prompt you to pay down variable-rate debt faster or lock in a fixed rate on a mortgage. Understanding these broader economic trends is not just for economists — it’s a critical part of a resilient financial plan and is key to developing smarter spending habits. The goal is to anticipate the financial punches before they land.
Over-Optimization vs. Real-Life Balance: The Frugal Fatigue
While tracking broader economic trends is smart, an equal danger lurks in our own spreadsheets and budgeting apps. Pushing frugality to its absolute limit can lead to a specific kind of burnout known as frugal fatigue. It’s the exhaustion that comes from relentlessly optimizing every single penny. This often causes people to completely abandon their financial goals, swinging from extreme saving to reckless spending.
The Mental Toll of Constant Deprivation
Think of extreme frugality like a crash diet. You might see rapid results initially, but the constant restriction is mentally draining and nearly impossible to maintain long-term. Saying “no” to every coffee with a friend, skipping all social events, and agonizing over a $2 price difference eventually takes its toll. The mental energy spent on constant self-denial can lead to decision fatigue, where you become too worn out to make wise choices in other areas of your life.
What most people miss is that your willpower is a finite resource. If you spend all of it resisting small pleasures, what’s left when you face a major financial decision? This constant state of scarcity can even mimic symptoms of anxiety, creating a life that feels defined by what you lack rather than what you have.
When Saving Becomes an Obsession
There’s a fine line between disciplined saving and a harmful obsession. A healthy financial plan should reduce stress, not create it. When the pursuit of a higher savings rate begins to damage your mental health and relationships, you’ve crossed that line. This is when a positive habit becomes a negative compulsion.
The fixation can become all-consuming. Instead of seeing money as a tool for a better life, it becomes the goal itself. This mindset is not only unsustainable but also robs you of the very life you’re supposedly saving for.
Impact on Relationships and Well-being
Obsessive penny-pinching rarely happens in a vacuum—it affects those around you. It can create tension with a partner who has different spending values or lead to social isolation when you decline every invitation. According to data from the American Psychological Association, arguments about money are a major source of conflict for nearly 73% of couples. Constant haggling over minor expenses can make loved ones feel devalued and turn your home into a stressful environment.
This is where the real cost emerges. You might save a few hundred dollars, but at the expense of a relationship or your own peace of mind. That’s a terrible trade.
Strategies for Sustainable Frugality
Finding balance is the key to long-term financial success. The goal is to create a system that works for you without causing burnout. Sustainable frugality is about being intentional with your money, not just restrictive.
Build in a “Fun” Budget: The 50/30/20 rule is a great starting point—50% for needs, 20% for savings, and a key 30% for wants. Giving yourself explicit permission to spend on things you enjoy removes the guilt and makes the whole process more sustainable. This is the core of developing smarter spending habits that last.
Automate Your Savings: Set up automatic transfers to your savings and investment accounts on payday. Once that money is out of sight, you can more freely spend what’s left without agonizing over every purchase. This “pay yourself first” method reduces the daily mental load of saving.
Focus on the Big Wins: Don’t sweat the small stuff. Instead of driving to three different stores to save $0.50 on milk, direct that energy toward negotiating your big-ticket items. A few calls to lower your car insurance, cell phone bill, or credit card interest rate can save you far more than a year’s worth of couponing.
Remember Your “Why”: Keep your long-term goals front and center. Are you saving for a down payment, a trip, or financial independence? Connecting your daily choices to a meaningful goal makes the sacrifices feel purposeful (and temporary) rather than like pointless deprivation.
Ultimately, a successful financial journey isn’t a sprint fueled by deprivation; it’s a marathon powered by conscious, sustainable choices that align with the life you want to live.
From Avoiding Mistakes to Building Financial Antifragility
Recognizing the common pitfalls of frugal living and smart spending is a critical first step, but the ultimate goal isn’t simply to play defense. True financial mastery isn’t about meticulously avoiding every possible error; it’s about building a financial system that is strong enough to withstand shocks and flexible enough to seize opportunities. It’s about developing financial antifragility—the ability to not just survive volatility, but to actually become stronger because of it.
This means shifting your focus from a purely subtractive mindset (what can I cut?) to an additive one (how can I optimize and grow?). Instead of spending an hour driving to save $5 on gas, could that hour be invested in learning a skill that increases your earning potential by thousands? Instead of fearing market downturns, do you have a system in place to see them as buying opportunities? This proactive stance transforms your financial plan from a fragile list of rules into a dynamic, living strategy that serves your life, not the other way around.
As you move forward, what is the single most impactful change you can make to shift from merely saving money to actively building a more resilient financial future?
Frequently Asked Questions
What are the most common budgeting mistakes people make?
The most common errors include creating an overly restrictive budget that leads to burnout and abandoning the plan. Another major mistake is ignoring small, frequent purchases—the ‘latte factor’—which can add up to a significant drain on resources without diligent tracking.
How can I tell if my ‘frugal’ purchase is actually a false economy?
A purchase is a false economy if its low initial price is outweighed by future costs. Consider the total cost of ownership, including reliability, maintenance needs, and expected lifespan. If a cheap item will require frequent repairs or early replacement, a higher-quality alternative is often the more frugal choice in the long run.
What are the biggest investment mistakes new investors should avoid?
New investors often make the mistake of chasing popular trends or ‘hot’ stocks, which are frequently overvalued by the time they invest. Other major errors include failing to diversify their portfolio, leading to excessive risk, and making emotional decisions to buy or sell based on short-term market fluctuations.
How do economic trends like inflation affect my frugal living strategy?
Inflation directly impacts your strategy by reducing your purchasing power, meaning your money buys less than it used to. It also often leads to higher interest rates, which increases the cost of carrying debt. A smart strategy involves adjusting your budget for higher costs and prioritizing the reduction of variable-rate debt.
Is it possible to be ‘too frugal’?
Yes, it’s possible to be too frugal. This occurs when penny-pinching results in a negative trade-off, such as wasting valuable time for minimal savings (opportunity cost) or buying low-quality goods that fail quickly. Extreme frugality can also negatively impact your quality of life and lead to burnout.
How can I avoid lifestyle creep and maintain smart spending habits?
To avoid lifestyle creep, commit to automatically increasing your savings or investment contributions with every raise you receive. It’s also important to regularly review your budget to ensure your spending aligns with your goals, not just your increased income. This intentionality helps maintain discipline as your earnings grow.
Matheus Neiva has a degree in Communication and a specialization in Digital Marketing. Working as a writer, he dedicates himself to researching and creating informative content, always seeking to convey information clearly and accurately to the public.