Advanced Economic Trends Analysis: A Practitioner’s Guide to Frugal Living & Smart Investing
Move beyond headline news and generic advice. This guide deconstructs macroeconomic indicators, advanced asset allocation strategies, and behavioral economics to offer a sophisticated framework for smart investing and resilient frugal living in a volatile world.
By: Lara Barbosa on October 5, 2026
Most financial advice is stuck on budgeting apps and index funds. But what if the real key to wealth lies in understanding the economic forces that most people ignore? The same headlines about inflation or jobs that cause panic for some are clear signals for the prepared practitioner, offering a distinct advantage to those who know how to read them.
This guide moves beyond the surface-level numbers. It’s about deconstructing macroeconomic indicators—like sector-specific employment trends and central bank communications—to see the story they tell about the future. This isn’t about becoming an economist; it’s about developing the foresight to protect your assets and optimize your spending before shifts in the market become common knowledge. It is the difference between reacting to the news and acting on intelligence.
We will explore a three-part framework for advanced financial management. First, we’ll dissect key economic data to separate predictive signals from lagging noise. Then, we will move into technical asset allocation strategies, including dynamic rebalancing and alternatives, designed for resilience in volatile times. Finally, we’ll delve into the practical application of behavioral economics to build sustainable frugal habits that withstand cognitive biases and decision fatigue. This is your manual for navigating the complex economic landscape with confidence.
Deconstructing Macroeconomic Indicators for Personal Finance
Most people see economic headlines about GDP growth or inflation and treat them as final scores in a game. For the advanced practitioner, these are just starting points. True insight comes from dissecting these macroeconomic indicators to understand the underlying forces that will eventually ripple into your own wallet, mortgage rate, and investment portfolio. It’s less about knowing the number and more about understanding the story the number is trying to tell.
This process is about separating signal from noise. The real skill is in identifying which data points predict future changes and which simply confirm what has already happened. Understanding this distinction is core to making smarter financial decisions.
Beyond the Headlines: Granular Data Interpretation
Thinking about economic data is a bit like checking your car’s dashboard. Some indicators are lagging, like an oil pressure warning light; they tell you a problem has already occurred. GDP is a classic lagging indicator because it measures economic output over a past quarter. While useful for confirming a recession, it doesn’t help you prepare for one. In contrast, leading indicators are like your fuel gauge—they give you a chance to act before you’re stranded. Examples include building permits, initial jobless claims, and the stock market itself.
What most people miss is the nuance within these categories. A report from the Conference Board might show a dip in the Leading Economic Index (LEI), but the real story is in the components. Was the dip caused by a drop in consumer confidence or a slowdown in new manufacturing orders? The former might suggest short-term spending cuts, while the latter could signal deeper, more systemic issues that will eventually lead to unmasking the invisible costs in supply chains and consumer prices.
Sector-Specific Employment Trends
The national unemployment rate is far too blunt an instrument for precise financial planning. A headline rate of 3.7% masks huge variations between industries. For instance, if the tech sector sheds 50,000 jobs while the healthcare sector adds 70,000, the net change is positive, but this trend has massive implications for investors, job seekers, and even regional housing markets. A software engineer in San Francisco and a nurse in Cleveland are living in completely different economies. Analyzing the Bureau of Labor Statistics’ JOLTS (Job Openings and Labor Turnover Survey) report by sector provides a much clearer picture of where economic strength—and weakness—lies.
The Interplay of Fiscal and Monetary Policy
Fiscal policy (government spending and taxation) and monetary policy (central bank actions on interest rates and money supply) are often discussed separately, but they are deeply intertwined. Imagine the government initiating a large infrastructure spending program (fiscal stimulus) at the same time the central bank is raising interest rates to fight inflation (monetary tightening). These opposing forces create uncertainty. Will the stimulus fuel more inflation, or will higher rates curb the growth it aims to create?
This tension directly impacts your finances. Fiscal policy can alter your tax burden, while monetary policy sets the baseline for what you pay on your mortgage and what you earn on your savings. Understanding their interaction is key to navigating economic currents with frugal foresight.
Central Bank Communications and Market Sentiment
Sometimes, what a central banker says is more important than what they do. The market’s reaction to the tone of a press conference—whether it’s perceived as “hawkish” (aggressive on inflation) or “dovish” (focused on growth)—can trigger significant shifts in asset prices. The underrated factor here is the interpretation of single words or phrases in official statements (—and yes, analysts really do argue over the removal of a single adjective).
But how does this high-level wordplay affect your budget? It directly influences investor confidence and market sentiment, which in turn impacts the value of your 401(k) and other investments. The behavioral psychology behind these market movements is a powerful force, often dictating how people make smarter financial decisions well before policy changes take effect.
Forecasting Inflationary Pressures and Consumer Behavior
The Consumer Price Index (CPI) is the most cited inflation metric, but it’s another lagging indicator. To get ahead of price changes, practitioners watch upstream data like the Producer Price Index (PPI), which tracks costs for domestic producers. A recent analysis from the Federal Reserve Bank of St. Louis suggests that a sustained 2% increase in the PPI often precedes a 0.8% rise in the core CPI within four to six months. This gives you a important window to adjust your budget.
Monitoring these pressures allows you to anticipate when to lock in prices for major purchases or shift spending habits. When shipping container costs rise or commodity futures spike, it’s a strong signal that the price of finished goods on store shelves will soon follow. For the frugal-minded, this isn’t just academic; it’s a direct call to action for smarter spending before the wave of inflation hits home.
Strategic Asset Allocation Amidst Volatility: An Advanced Framework
Beyond the classic 60/40 portfolio, a more refined approach to asset allocation is necessary when markets become unpredictable. For the seasoned investor, static set-and-forget strategies are insufficient. The real work involves actively managing your mix of assets in response to changing conditions, much like a sailor adjusting the sails to catch shifting winds instead of just holding the rudder straight and hoping for the best.
This isn’t about timing the market perfectly. It’s about probabilities and risk management. The goal is to build a portfolio resilient enough to withstand shocks while being flexible enough to capture opportunities. This is active management.
Dynamic Rebalancing and Tactical Adjustments
A static asset allocation is a solid foundation, but dynamic rebalancing takes it a step further. Instead of rebalancing on a fixed schedule (like annually), this strategy involves adjusting your holdings based on market movements. For instance, if stocks have a stellar run and grow from 50% to 60% of your portfolio, you would sell off that 10% gain and reinvest it into underperforming assets to return to your target. What most people miss is that rebalancing isn’t just about risk; it’s a disciplined way to systematically buy low and sell high.
Tactical adjustments are even more active, involving short-term deviations from your long-term strategy to capitalize on specific market views. These moves are often informed by a deep understanding of economic indicators and market sentiment. The data suggests—though not conclusively—that these tactical shifts can add percentage points to returns, but they also introduce the risk of being wrong. The key is to make small, calculated bets rather than wholesale changes, understanding the behavioral science of wealth and avoiding panic-driven decisions.
Leveraging Economic Cycle Analysis for Portfolio Shifts
Understanding where we are in the economic cycle is critical for making effective tactical shifts. For example, during an early-cycle recovery, cyclical stocks and high-yield bonds often perform well as economic activity accelerates. As the cycle matures and heads toward its peak, inflation might become a concern, making inflation-protected securities (TIPS) and commodities more attractive. But how do you know when to shift? This is where analyzing leading indicators, as we’ve discussed, becomes significant for anticipating what’s next for your portfolio.
Integrating Alternative Investments for Diversification
Traditional stocks and bonds are no longer the only game in town for diversification. Alternative investments offer return streams that are often uncorrelated with public markets, providing a valuable buffer during downturns. A Morningstar analysis found that portfolios with even a 10% allocation to alternatives showed better risk-adjusted returns over the last market cycle. These assets can help smooth out portfolio returns and protect against the kind of volatility that rattles purely public-market investors.
Real Estate, Private Equity, and Commodities
Among the most accessible alternatives are real estate (through REITs or direct ownership), private equity (often via specialized funds), and commodities. Real estate can provide steady income and an inflation hedge. Private equity offers access to young, high-growth companies before they go public, though it comes with higher risk and long lock-up periods. Commodities like gold and oil have their own unique cycles, often moving inversely to the broader stock market—think of them as financial shock absorbers.
Risk Parity vs. Traditional Diversification
Modern portfolio theory has evolved, leading to strategies like Risk Parity. Unlike traditional diversification, which allocates capital (e.g., 60% stocks, 40% bonds), Risk Parity allocates based on risk. Since stocks are historically more volatile than bonds, a traditional 60/40 portfolio actually gets most of its risk from the stock portion. Risk Parity attempts to balance the risk contribution from each asset class, which often means using leverage to increase the position size of lower-risk assets like bonds.
This approach aims to create a more balanced portfolio where no single asset class can dominate the portfolio’s swings. Here’s a simplified comparison with another advanced model, the Permanent Portfolio, which allocates capital equally:
Feature
Permanent Portfolio
Risk Parity
Allocation Method
Equal capital allocation (25% each to stocks, long-term bonds, cash, and gold).
Equal risk contribution from each asset class; capital allocation varies.
Use of Leverage
None. The strategy is simple and unleveraged.
Often uses leverage on lower-risk assets (like bonds) to achieve risk balance.
Primary Goal
Capital preservation and stability across all economic conditions (prosperity, recession, inflation, deflation).
Achieve smoother returns and better risk-adjusted performance by balancing risk sources.
Choosing between these advanced models depends heavily on an investor’s risk tolerance, complexity preference, and long-term financial outlook. Understanding these frameworks is a core part of navigating economic currents with foresight. The decision itself reflects a deep understanding of not just market mechanics, but one’s own financial and psychological limits.
If you want to encourage someone to do something, make it easy.
— Richard H. Thaler & Cass R. Sunstein, Nudge: Improving Decisions About Health, Wealth, and Happiness
Feature
Permanent Portfolio
Risk Parity
Allocation Method
Equal capital allocation (25% each to stocks, long-term bonds, cash, and gold).
Equal risk contribution from each asset class; capital allocation varies.
Use of Leverage
None. The strategy is simple and unleveraged.
Often uses leverage on lower-risk assets (like bonds) to achieve risk balance.
Primary Goal
Capital preservation and stability across all economic conditions (prosperity, recession, inflation, deflation).
Achieve smoother returns and better risk-adjusted performance by balancing risk sources.
Optimizing Frugal Practices Through Behavioral Economics
Understanding refined asset allocation is only half the battle. The other half is fought inside your own head, where cognitive biases can quietly sabotage the most well-laid financial plans. The underrated factor here is that our brains are wired for survival, not for navigating the complexities of modern finance. This is where behavioral economics becomes an primary tool for the advanced frugal practitioner.
Principles like loss aversion—the tendency to feel the pain of a loss more acutely than the pleasure of an equivalent gain—and mental accounting dictate our financial choices more than we realize. What most people miss is how these mental shortcuts can undermine even the most disciplined budget. Recognizing these patterns is the first step toward building a more resilient financial life, a concept explored in the behavioral science of wealth.
Harnessing Nudges for Sustainable Savings
Choice architecture, a concept popularized by Nobel laureate Richard Thaler, shows how the presentation of choices influences our decisions. We see this with supermarket layouts and default 401(k) contributions, but how often do we apply that same logic to our own spending habits? You can create “nudges” in your own life to make saving the path of least resistance. This is much simpler than it sounds.
Automating a weekly transfer of $57 into a high-yield savings account right after your paycheck hits is a classic example. You’re designing a system where the default action is saving. The data suggests this works; a report from the National Bureau of Economic Research found that automatic enrollment in savings plans can increase participation rates by over 50 percentage points. This simple setup helps bypass the daily debate of whether to save or spend, making consistent progress nearly effortless.
Overcoming Decision Fatigue in Spending
Every choice you make, from what to wear to which project to tackle first, depletes a finite reserve of mental energy. By the end of the day, this “decision fatigue” can lead to poor financial choices—which is why that late-night online shopping spree feels so inevitable. It’s like trying to follow a complex recipe after an exhausting day at work; you’re far more likely to just order a pizza.
Fighting this requires building systems to reduce the number of financial decisions you make daily. You can start by identifying the cognitive traps that cost you money and implementing countermeasures to avoid common mistakes in frugal living. A simple checklist can help you audit your own behavior:
Automate Core Expenses: Set up automatic payments for all recurring bills and savings contributions to remove them from your daily decision-making process.
Implement Spending Rules: Use mental accounting to your advantage by creating firm rules, such as “I only eat out on Fridays” or “Any unexpected income goes directly into my investment account.”
Create a 24-Hour Rule: For any non-necessary purchase over a set amount, like $100, enforce a mandatory 24-hour waiting period. This simple delay often dissolves the initial impulse.
Limit Your Options: Instead of browsing endlessly, identify just two or three pre-vetted options for a needed purchase. This reduces analysis paralysis and conserves mental energy.
Mastering these internal triggers doesn’t just save money; it frees up cognitive bandwidth for more important financial planning and strategic thinking about your long-term financial outlook.
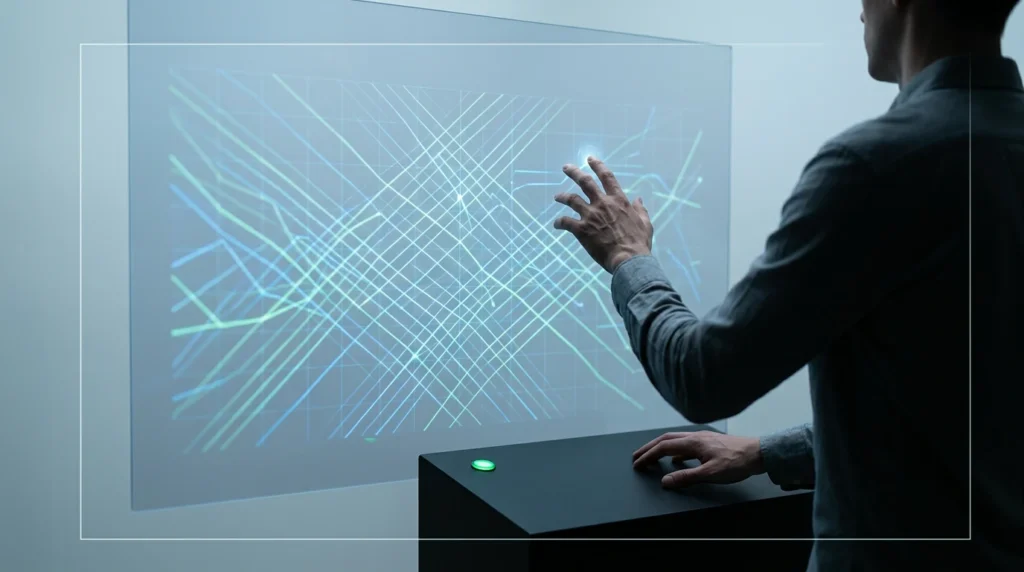
A person analyzes complex economic data visualizations on a translucent screen, illustrating macroeconomic indicators and their impact on personal finance.
Leveraging Data Analytics for Smart Spending Decisions
While understanding behavioral biases is a major step, modern financial technology allows you to put that knowledge on autopilot. Advanced personal finance platforms move beyond simple spreadsheets by automatically categorizing your spending and flagging transactions that align with known cognitive traps. What most people miss is that these tools aren’t just for tracking; they’re for actively decoding the behavioral science of your own wealth. It’s like having a digital coach who points out when you’re about to make a financially questionable decision.
The real power lies in identifying patterns you didn’t know existed. Many apps now allow custom tagging to track discretionary spending—like “stress-induced takeout” or “boredom shopping”—which can be incredibly revealing. This process is like running a diagnostic on your financial engine, looking for the small leaks that drain your resources over time. A report by the American Institute of CPAs noted that households using financial aggregation apps saved an average of 12.7% on recurring bills by identifying and canceling unused subscriptions. These are the kinds of hidden costs that technology makes visible.
The patterns are often surprising.
Beyond retrospective analysis, the most advanced software uses your historical data to forecast future cash flow with impressive accuracy. Some platforms can model the long-term financial impact of a major purchase, showing you how buying a new car today might affect your retirement savings two decades from now. This predictive capability transforms your budget from a restrictive document into a strategic tool for navigating your financial future with greater foresight.
Ultimately, this level of data analysis isn’t just about pinching pennies—it’s about optimizing capital allocation. By identifying a few hundred dollars in inefficient spending, you free up that money for more productive uses, like increasing your contributions to an investment account. The goal is to make your money work smarter, not just to spend less of it.
Scenario Planning: Stress-Testing Your Financial Resilience
Moving beyond simple data tracking involves actively preparing for financial shocks. Stress-testing isn’t just a practice for large banks; it’s a powerful technique for any individual serious about building true financial resilience. It’s about asking tough questions before a crisis forces you to. After all, a plan that only works when everything goes right isn’t much of a plan at all.
The reality is that financial stability can be fragile. According to a recent Federal Reserve report, a surprising 37% of adults would struggle to cover an unexpected $400 expense using cash or its equivalent. This highlights a widespread vulnerability that advanced planning can directly address. By simulating economic downturns or personal emergencies, you can identify weak points in your budget and fortify them before they break.
Developing ‘What If’ Models for Income and Expenses
Creating ‘what if’ scenarios is like running a fire drill for your finances. The goal is to see how your budget holds up under pressure. Start by identifying the most significant variables in your financial life—usually your primary income source and your largest expense categories like housing, food, and transportation. From there, you can model specific adverse events.
What happens if your income is cut by 25% for six months? How does your budget react if sudden inflation reveals the invisible costs in your regular spending, increasing your grocery and fuel costs by 18%? You can use a simple spreadsheet to map these scenarios out. Input your current numbers, then create columns that apply these stressors. The point where your outflow consistently exceeds your inflow is your breaking point, and understanding that is critical for making smarter decisions under duress.
This process reveals exactly how much buffer you actually have.
Building Dynamic Emergency Funds
The results of your stress test directly inform a more refined approach to emergency savings. The old “three to six months of expenses” rule is a decent starting point, but it’s far too generic for a practitioner’s strategy. A dynamic emergency fund, is tailored to your specific risks identified during scenario planning.
Think of it less like a single spare tire and more like a complete roadside assistance kit with tools for different problems. If your stress test reveals a high sensitivity to income loss due to a volatile job market, your fund should be larger, perhaps closer to nine months of necessary expenses. Conversely, if you have multiple, stable income streams, a smaller, more nimble fund of four months might be sufficient. The underrated factor here is liquidity.
Consider a tiered structure: a small amount (e.g., one month’s expenses) in an instant-access checking account for immediate crises, with the larger remainder in a high-yield savings account. This structure provides both security and better returns, ensuring you are prepared for whatever tomorrow’s wallet might need to handle. Your emergency fund becomes an adaptable tool, not just a static pile of cash.
Integrating ESG Factors into Frugal and Investment Choices
Moving beyond basic spreadsheets and budgets means aligning your money with your values. This is where Environmental, Social, and Governance (ESG) principles come into play. It’s not just about philanthropy; it’s a technical layer of risk analysis. In fact, a study from MSCI found that companies with high ESG ratings experienced lower costs of capital and lower stock price volatility compared to their lower-rated peers over a five-year period. This data suggests a clear financial incentive.
For investors, this involves scrutinizing a fund’s holdings beyond its name—a “green” fund might still hold companies with questionable labor practices. Using platforms that provide detailed ESG scoring can reveal the invisible costs and risks tied to a company’s operations. Think of it less like picking a team and more like scouting individual players for their long-term potential and character.
This same mindset applies to frugal living. Ethical consumption means investigating where your money goes, from choosing coffee brands that pay fair wages to supporting local businesses that invest back into the community. It reframes frugality from mere penny-pinching into a powerful tool for personal and societal impact. This approach acts as your financial compass, guiding both saving and spending decisions. The real challenge becomes balancing cost-effectiveness with these deeper ethical considerations.
Beyond the Data: Are You Prepared for the Next Financial Frontier?
Having mastered the interplay of macroeconomic data and behavioral discipline, the journey doesn’t end. The principles of analysis and self-awareness are timeless, but the tools are constantly evolving. As artificial intelligence becomes more adept at parsing vast datasets, will personalized economic forecasting become the new standard, making today’s advanced techniques seem quaint? Perhaps the most significant future risk isn’t a market crash, but a failure to adapt our own skills and mindset to a world where financial advantage is redefined. The ultimate question then becomes: what are you investing in beyond your portfolio?
Frequently Asked Questions
How do expert investors use yield curve inversions to predict recessions?
Expert investors view an inverted yield curve, where short-term government bond yields exceed long-term yields, as a strong recession predictor. This phenomenon signals market pessimism about long-term growth and tightens bank lending, as their profit margins shrink. This credit crunch often precedes a broader economic slowdown.
What are the most overlooked behavioral biases that impact seasoned investors?
Even seasoned investors are susceptible to overconfidence bias, leading them to trade too frequently and underestimate risks. Another is confirmation bias, where they seek out information that validates their existing beliefs and ignore contradictory data, causing them to hold onto losing positions for too long.
Can advanced data analytics predict personal financial ‘black swan’ events?
By definition, ‘black swan’ events are unpredictable, so analytics cannot forecast them directly. advanced data models can perform rigorous stress tests on a portfolio, simulating the impact of extreme, low-probability events. This helps build financial resilience and identify vulnerabilities, preparing an investor for shocks without predicting their specific cause.
How does geopolitical instability influence long-term frugal living strategies?
Geopolitical instability directly impacts frugal strategies by creating supply chain volatility and unpredictable inflation. This forces a shift from simple budgeting to building resilience. Advanced frugal living involves diversifying income, securing primary goods ahead of price spikes, and prioritizing adaptable skills that hold value across different economic scenarios.
What role do complex derivatives play in advanced personal investment portfolios?
In advanced portfolios, complex derivatives like options serve specific strategic roles beyond simple growth. They are primarily used for hedging to insure against market downturns or for generating income through strategies like selling covered calls. While they add risk and complexity, they allow for precise risk management not achievable with stocks alone.
Lara Barbosa has a degree in Journalism, with experience in editing and managing news portals. Her approach combines academic research and accessible language, turning complex topics into educational materials of interest to the general public.