Navigating Tomorrow’s Wallet: Emerging Trends in Frugal Living and Smart Spending
Feeling the financial squeeze? Yesterday's money advice is obsolete. This guide explores the new rules of personal finance, from leveraging the circular economy and AI-powered apps to avoiding digital spending traps and starting to invest with just spare change. Reclaim control of your wallet in today's complex economy.
By: Matheus Neiva on September 23, 2026
That persistent feeling of your paycheck not stretching as far as it used to isn’t just in your head. In a landscape of rising costs and economic uncertainty, the old rules of personal finance—like simply cutting coupons or skipping a daily coffee—are proving woefully inadequate. The ground has shifted, and navigating this new terrain requires more than just discipline; it demands a completely new map and a modern set of tools. Yesterday’s advice feels disconnected from a world where your smartphone is both your biggest savings asset and your most dangerous spending liability.
The challenges are complex and interconnected. It’s not just inflation making groceries more expensive; it’s also fluctuating interest rates changing the math on every loan, from credit cards to mortgages. At the same time, the digital marketplace has been engineered to perfection, using advanced psychology to encourage frictionless, impulsive spending. This combination of external economic pressures and internal digital temptations creates a perfect storm that can easily capsize even the most well-intentioned budget.
This guide is designed to be your new financial playbook. We will dissect the key economic currents affecting your daily life, from inflation’s grip to the real cost of borrowing. Then, we’ll move beyond outdated frugality to explore innovative strategies like the circular economy, tech-driven savings, and community resource sharing. Finally, you’ll learn to identify and combat modern spending pitfalls, align your purchases with your values, and take your first confident steps into the world of investing, no matter how small you start. It’s time to stop feeling overwhelmed and start taking control.
The Shifting Landscape: Understanding Current Economic Currents
Let’s be blunt: the economic ground beneath your feet is shifting, and pretending otherwise is financial suicide. The gentle, predictable currents of the past have given way to volatile rapids driven by forces that directly target your wallet. What most people miss is that these aren’t abstract news headlines; they are active drains on your purchasing power. Understanding these shifts isn’t just academic—it’s the first step toward building a financial defense. Your ability to navigate economic shifts with smart spending will determine whether you sink or swim.
This isn’t just a feeling. It’s a calculated reality.
Decoding Inflation’s Grip on Your Groceries and Bills
The most obvious assault on your budget is inflation. It’s the silent thief that makes your paycheck feel smaller, even if the number stays the same. That weekly grocery run that used to cost $150 now easily tops $190, and it’s not because you suddenly developed a taste for imported cheese. A recent analysis from the U.S. Department of Agriculture found that food-at-home prices saw a staggering 5.8% jump over a 12-month period, driven by persistent supply chain disruptions and higher energy costs.
This isn’t a temporary blip. This is the new baseline. Managing your money now requires a more aggressive strategy than just clipping coupons. It means fundamentally re-evaluating where every dollar goes and developing smarter spending habits to counteract the constant price creep on essentials. Ignoring it is like trying to fill a bucket with a hole in it; your efforts are pointless without first plugging the leak.
Interest Rates and Borrowing: What Every Frugal Spender Needs to Know
While inflation attacks your cash, fluctuating interest rates attack your debt. When the Federal Reserve adjusts rates to manage the economy, it creates a direct ripple effect on consumer borrowing costs. Suddenly, the interest on your credit card balance, a new car loan, or a potential mortgage can become significantly more expensive. Think of it as the price of borrowing money going up.
Dr. Alan Krueger, an economist at the Peterson Institute for International Economics, explains, “Consumers must understand that a 2% hike in the federal funds rate can translate to thousands of dollars in extra interest payments over the life of a typical home or auto loan.” This makes big-ticket purchases a much heavier lift and can derail long-term financial goals. For anyone committed to frugal living, this environment demands a near-zero tolerance for carrying high-interest debt. It fundamentally changes the math on whether it’s better to save up for a purchase or finance it, making a solid blueprint for economic shifts more important than ever.
The key takeaway is that the rules have changed. The passive financial habits that worked before are now liabilities, pushing proactive budget management from a “good idea” to a critical survival skill.
Frugal Living Reimagined: Innovative Strategies for Modern Savers
Forget your grandmother’s dusty coupon box and obsessive penny-pinching. That outdated image of frugality is dead. Today’s smart savers are playing an entirely different game—one of strategic efficiency, not just painful sacrifice. This new approach leverages technology, community, and a complete reevaluation of ownership to build financial resilience, forming a core part of an effective smart spending blueprint for economic shifts.
This isn’t about simply spending less; it’s about spending smarter by tapping into powerful systems. The most effective strategies are found within the circular economy, tech-driven automation, and community-based resource sharing. These aren’t just buzzwords; they are practical frameworks for getting more value out of every dollar.
The Rise of the Circular Economy: Beyond Second-Hand
The circular economy challenges the very idea of a product’s “end of life.” Instead of a linear path from factory to landfill, it promotes a system where goods are designed for durability, repair, and reuse. According to the Ellen MacArthur Foundation, a widespread shift to this model offers significant economic benefits by drastically reducing waste and resource consumption. It’s more than just shopping at a thrift store; it’s a systemic change in how we view material goods.
This is a revolution in consumer rights. “Right to repair” legislation is gaining momentum, pushing back against manufacturers who make it nearly impossible to fix your own electronics or appliances. Having access to parts and manuals means you can extend the life of a smartphone for a few dollars instead of being forced into a thousand-dollar upgrade. Reclaiming control over your possessions is a critical component of any modern guide to smarter spending habits.
Tech-Driven Frugality: Apps, AI, and Automation for Your Wallet
Your smartphone has become one of the most powerful saving tools you can own. Modern budgeting apps have evolved far beyond simple expense logs. They now employ artificial intelligence to analyze your spending, identify wasteful patterns, and find savings opportunities you would have missed. These apps function like a personal CFO in your pocket—an always-on analyst dedicated to your financial health.
For instance, services like Trim and Rocket Money automatically negotiate recurring bills and cancel forgotten subscriptions. A survey by C+R Research suggests such tools can save the average user between $50 and $150 annually with minimal effort. But are you comfortable handing over that much control to an algorithm? The convenience is undeniable, but it requires a leap of faith in the technology managing your finances. The underrated factor here is the reduction in decision fatigue. By automating small financial choices, you free up the mental bandwidth needed for more complex smart spending strategies.
Community-Based Resource Sharing: New Avenues for Savings
Individual ownership is becoming an expensive and inefficient model for many items. Why should ten houses on one street each own a lawnmower that sits unused 99% of the time? This simple question is driving a powerful movement toward collaborative consumption, where access trumps ownership. It’s a model that saves money while simultaneously building stronger community bonds.
This is happening right now in neighborhoods everywhere.
Skill Swapping and Bartering Networks
The ancient practice of bartering has been reborn in the digital age. Online platforms and local social media groups facilitate a cashless economy where skills are the currency. A graphic designer might trade a logo design for plumbing repairs, or a talented cook could exchange meal prep services for childcare. It’s a direct, value-for-value transaction that sidesteps traditional income and expenses.
These networks foster a micro-economy built on human talent and mutual trust. The benefit is not purely financial; it validates a wider range of skills and strengthens the social fabric of a community, a key aspect for anyone looking to navigate economic shifts through frugal living.
Local Food Share Initiatives
Food waste represents a staggering loss of money and resources. The Natural Resources Defense Council (NRDC) reports that up to 40% of the food supply in the United States goes uneaten. Innovative initiatives are capturing this surplus and redirecting it to households. Apps like Too Good To Go partner with restaurants and grocery stores to sell end-of-day “surprise bags” of perfectly good food for a fraction of the retail price.
Beyond digital solutions, grassroots efforts like community fridges and food co-ops provide physical locations for neighbors to share excess produce from gardens or pantries. This approach tackles household budget strain and food insecurity at the source. The future of saving money may involve looking less at your bank account and more toward your neighbor.
Consumers must understand that a 2% hike in the federal funds rate can translate to thousands of dollars in extra interest payments over the life of a typical home or auto loan.
— Dr. Alan Krueger, Economist at the Peterson Institute for International Economics
Strategy Area
Key Tactic
Primary Benefit
Economic Awareness
Track Inflation & Interest Rates
Protects purchasing power and informs borrowing decisions.
Modern Frugality
Embrace the Circular Economy
Reduces waste, lowers long-term costs, and promotes repair over replacement.
Tech-Driven Savings
Use AI Budgeting & Bill Negotiation Apps
Automates savings, cancels unused subscriptions, and identifies wasteful patterns.
Curbs impulse purchases and encourages conscious decision-making.
Ethical Consumption
Research Brand Values & Supply Chains
Aligns spending with personal ethics and supports sustainable practices.
Beginner Investing
Utilize Micro-investing Apps & Low-Cost ETFs
Builds wealth with minimal initial capital and diversifies risk.
Smart Spending in the Digital Age: Avoiding New Pitfalls
Your smartphone has become a financial battleground, and most people are losing the war without even knowing a fight is happening. Every tap, scroll, and click is an opportunity for companies to siphon money from your account, often with your blissful permission. This isn’t about blaming technology; it’s about recognizing that the architecture of the digital economy is designed for frictionless spending, not conscious saving.
The convenience we crave has a hidden, compounding cost. What most people miss is that the path of least resistance—one-click ordering, saved payment details, “buy now, pay later” schemes—is a carefully constructed slide leading directly away from financial health. It’s time to stop sleepwalking through your digital transactions and start asking tougher questions.
Unmasking Subscription Creep: Are You Paying for What You Use?
That “free trial” you signed up for six months ago is likely still draining your bank account. Subscription creep is the slow, silent accumulation of recurring charges for services you’ve forgotten or barely use. It’s like leaving a tap dripping; a single drop is nothing, but over a year it fills a bathtub. A recent study from C+R Research found that consumers estimate they spend around $86 per month on subscriptions, but the actual average is closer to $219.
This discrepancy isn’t just bad memory; it’s a design feature. Companies bank on your inertia. The effort required to find the cancellation page, log in, and confirm your choice is often just enough to make you put it off until next month. The first step to reclaiming control is a ruthless audit. Go through your bank and credit card statements line by line and ask a simple question for each recurring charge: did I get my money’s worth last month? If the answer is no, it’s time to cancel. It’s that simple.
Combatting Impulse Buys: Strategies for Online Shopping
Online retailers have perfected the art of turning a “maybe” into a “yes” in under three seconds. They use a potent cocktail of limited-time offers, social proof (“17 people just bought this!”), and algorithmically personalized ads that follow you across the internet. This isn’t just good marketing; it’s a form of psychological manipulation designed to bypass your rational brain.
To fight back, you need to introduce friction into your buying process. Delete saved credit card information from browsers and apps, forcing you to manually enter it for each purchase. This small act provides a important pause for reflection. Implement a mandatory 24-hour waiting period for any non-required purchase over a certain amount, say $50. You’d be surprised how many “must-have” items feel completely unnecessary the next day. These are not just tips; they are primary defensive maneuvers for anyone serious about thriving on a budget in today’s economy.
Ethical Consumption: Aligning Values with Your Spending
Every dollar you spend is a vote for the kind of world you want to live in. Yet, in the rush for convenience and low prices, it’s easy to fund companies whose practices are completely at odds with your personal values. Conscious consumption demands more than just finding a good deal; it requires a deeper look into the companies you support. This shift moves beyond basic frugality and into a more holistic view of smarter spending habits.
Researching Brand Values and Supply Chains
It’s no longer enough to take a company’s “About Us” page at face value. True research means digging into third-party certifications (like B Corp or Fair Trade), reading reports from watchdog organizations, and looking for transparency in their supply chain disclosures. Does the company publish information about its factory locations and labor practices? What is its stated policy on environmental impact, and is there evidence to back it up? This isn’t a quick process—it takes effort—but it transforms you from a passive consumer into an active economic participant.
The True Cost of ‘Fast’ Fashion and Goods
The allure of a $10 shirt or a $5 gadget is powerful, but the real price is paid elsewhere—by underpaid workers and a polluted planet. The fast fashion industry, for example, is responsible for an estimated 10% of global carbon emissions, according to the United Nations Environment Programme. The business model relies on creating a constant sense of need and disposability, leading to mountains of textile waste.
This is where the math gets ugly.
Buying one well-made, ethically sourced item that lasts for years is almost always cheaper in the long run than buying and replacing a dozen poorly made alternatives. The challenge is shifting your mindset from immediate gratification to long-term value, understanding that the lowest price tag rarely reflects the true cost of an item.
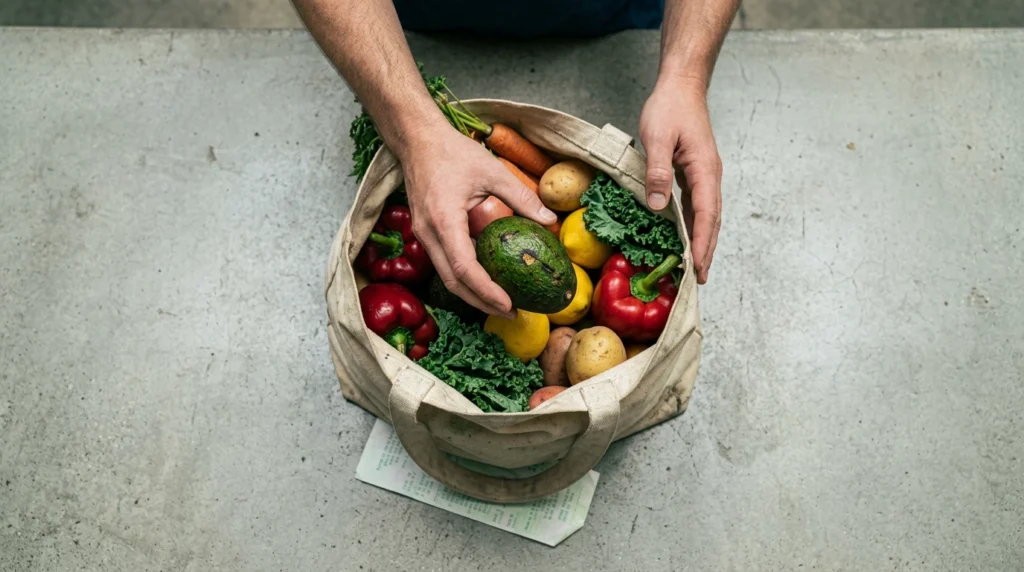
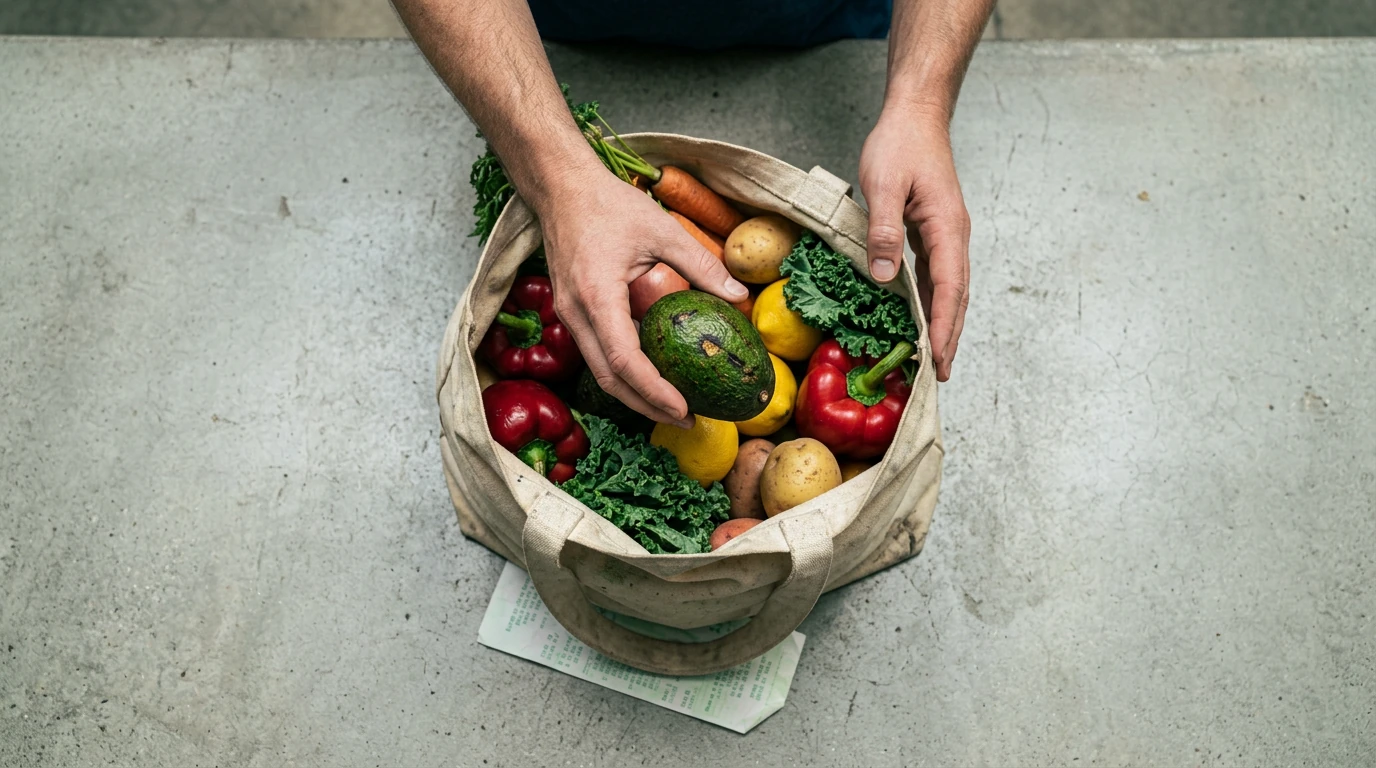
A person’s hands carefully placing an avocado into a reusable shopping bag filled with fresh produce, on a concrete counter with a grocery receipt, illustrating the impact of economic shifts on household budgets.
Investment Basics for the Budget-Conscious: New Avenues
For decades, the world of investing felt like a walled garden, reserved for those with hefty bankrolls and private advisors. That era is over. The rise of micro-investing platforms has completely changed the game, allowing you to invest spare change from everyday purchases. It’s the digital equivalent of a piggy bank, but one where your money is actually put to work, turning your smart spending for frugal living into a potential wealth-building engine.
Once you’re comfortable, low-cost Exchange-Traded Funds (ETFs) offer the next logical step. Think of them as a basket containing dozens or even hundreds of different stocks or bonds, which diversifies your risk without requiring you to be a stock-picking genius. You get a slice of the entire market for a fraction of the cost previously possible, a key component for anyone building effective money strategies in today’s economy.
But what if you want your money to do more than just grow? The underrated factor here is the explosion in socially responsible investing (SRI). This isn’t just a niche trend; a recent report from the Forum for Sustainable and Responsible Investment noted that professionally managed sustainable investment assets represent a significant portion of the total U.S. assets under management. It means you can actively choose funds that align with your ethical values—from renewable energy to fair labor practices—without necessarily sacrificing returns.
This democratization of finance puts historic power directly into your hands. The real question is no longer if you can invest, but how you will choose to.
Future-Proofing Your Finances: Adapting to Economic Volatility
Investing is a powerful wealth-building tool, but let’s be blunt: it’s not a shield. Placing bets on the market without a solid foundation is like building a skyscraper on sand. The real secret to financial security isn’t just about picking the right ETF; it’s about building a personal economic fortress that can withstand unexpected shocks. This requires a shift in mindset from pure growth to deliberate resilience.
Your financial plan needs to be ready for anything. The underrated factor here is anticipating volatility not as a possibility, but as a certainty.
Building a strong Emergency Fund: More Critical Than Ever
The concept of an emergency fund is hardly new, but its definition has changed. The old “three to six months of expenses” advice feels dangerously outdated in an economy defined by rapid shifts and unpredictable job markets. A recent Federal Reserve report highlighted that a shocking 37% of American adults couldn’t cover a mere $400 emergency expense with cash. Are you part of that statistic?
Debate rages over where to keep this cash. A high-yield savings account (HYSA) offers liquidity, but its returns often barely keep pace with inflation. Then there are strategies like laddering I-Bonds, which offer inflation protection but tie up your money for at least a year. Some even advocate for keeping a portion in a low-risk brokerage account, accepting minor market risk for potentially higher returns. The right answer depends entirely on your personal risk tolerance and the stability of your income. What most people miss is that the perfect strategy doesn’t exist—the best one is the one you can actually stick to while refining your guide to smarter spending habits.
Exploring Side Hustles and Passive Income Streams
Relying on a single paycheck is the financial equivalent of having only one route for your daily commute. The moment there’s a roadblock—a layoff, an illness, a corporate restructuring—you’re completely stuck. Diversifying your income streams provides alternative routes, creating a buffer that protects your core financial health. This isn’t just about making more money; it’s about decentralizing your economic risk.
The gig economy has made this more accessible than ever before. According to an Upwork study, nearly 60 million Americans engaged in freelance work over the past year. This can range from active side hustles like consulting in your field or driving for a rideshare service to more passive income sources like creating a digital product or renting out unused storage space. Each new stream of income, no matter how small, adds another layer of protection to your bottom line, reinforcing the smart spending habits you develop in evolving economic landscapes.
Ultimately, financial resilience isn’t a destination you arrive at (sorry, there’s no finish line). It is a continuous practice of learning, adapting, and questioning the assumptions that underpin your financial life. The economic climate will continue to shift, and your ability to pivot with it will determine your long-term security.
From Frugal Tactics to Financial Philosophy
You now have a toolkit of modern strategies to defend your budget and build wealth in a complex economic environment. But after mastering the tactics of smart spending and strategic saving, a more profound question emerges: What do you want your money to achieve beyond mere accumulation or survival? As you reclaim dollars from wasteful subscriptions and impulse buys, you’re not just padding an account; you’re freeing up resources. Will you direct that newfound capital toward investments that reflect your values, experiences that enrich your life, or causes that shape a better community? The ultimate act of financial empowerment isn’t just changing how you spend, but consciously deciding what your money is for.
Frequently Asked Questions
How do current economic trends specifically affect my everyday spending?
Current economic trends impact you directly in two major ways. First, inflation reduces your purchasing power, meaning the same amount of money buys you less, which is most noticeable in rising grocery and gas prices. Second, fluctuating interest rates make borrowing money for things like credit card debt, car loans, or mortgages more expensive, increasing your monthly payments.
What are some new, innovative ways to save money that weren’t common a few years ago?
Modern saving goes beyond coupons. Key innovations include participating in the ‘circular economy’ by repairing electronics instead of replacing them, using AI-powered apps to automatically cancel forgotten subscriptions, and engaging in community resource sharing like tool libraries or skill-swapping networks to get what you need without spending money.
Is it still a good time to start investing with economic uncertainty?
Yes, it can be an excellent time to start, especially with a long-term perspective. Modern tools like micro-investing apps allow you to invest small amounts consistently, a strategy known as dollar-cost averaging. This approach can help smooth out market volatility over time, making economic uncertainty less of a barrier to building wealth.
How can I distinguish between a good deal and a marketing trap in the current market?
A good deal provides genuine, long-term value, often seen in a well-made, durable item that costs less over its lifespan. A marketing trap creates false urgency with ‘limited-time offers,’ encourages impulse buys on low-quality goods, and often uses ‘buy now, pay later’ schemes to obscure the true total cost of an item.
What role does technology play in both saving and spending smartly today?
Technology is a double-edged sword for your finances. On one hand, it empowers you to save with budgeting apps, automatic bill negotiators, and investment platforms. On the other, it facilitates overspending through one-click ordering, hyper-targeted advertising, and addictive ‘buy now, pay later’ services that make impulse buying dangerously easy.
Matheus Neiva has a degree in Communication and a specialization in Digital Marketing. Working as a writer, he dedicates himself to researching and creating informative content, always seeking to convey information clearly and accurately to the public.