Unmasking the Invisible Costs: What Economic Trends & Smart Spending Hide
Official inflation numbers are misleading. Your wallet is being drained by invisible forces like shrinkflation, psychological biases, and hidden fees. This guide unmasks these hidden costs and provides a framework for smart spending to reclaim your financial power.
By: Matheus Neiva on October 5, 2026
Last updated on: October 15, 2026
Does it feel like your money is disappearing, even when your income stays the same? You’re not imagining it. While official reports talk about moderate inflation, your grocery bills, subscription fees, and utility costs tell a much more alarming story. The most significant threats to your financial well-being aren’t always the big, headline-grabbing economic shifts; they are the subtle, invisible costs engineered to drain your wallet without you ever noticing.
This financial erosion is happening on multiple fronts. On one side, manufacturers quietly shrink the products you buy and degrade their quality to protect their profits. On the other, your own mind works against you, with deep-seated psychological biases pushing you toward impulsive decisions that sabotage your best-laid financial plans. These internal and external forces create a perfect storm, making smart spending feel like a constant, uphill battle.
This article unmasks these hidden financial drains. We will deconstruct the mechanics of shrinkflation and skimpflation, explore the cognitive traps like ‘present bias’ and ‘mental accounting’ that derail your budget, and reveal how distant global supply chain issues directly inflate your local costs. By illuminating these invisible forces, you’ll gain the critical awareness needed to move from being a passive consumer to an active architect of your financial future.
The Silent Erosion: Inflation’s Subtleties Beyond Price Tags
You’re being lied to about inflation. The official numbers tell one story, but your bank account tells another. The most dangerous economic trends aren’t the ones screaming from headlines; they are the subtle, creeping changes that drain your wallet while you’re looking the other way. This isn’t just about prices going up; it’s about value disappearing right before your eyes.
Most people fixate on the Consumer Price Index (CPI), but what most people miss is that this figure is just an average. Your personal inflation rate is likely much higher, especially if your budget is heavy on food, fuel, and housing. The data suggests that while the general inflation rate might be reported at 3.4%, grocery costs for the same period have jumped over 5.8%, according to the Bureau of Labor Statistics. It’s a quiet theft of your future wealth.
Shrinkflation & Skimpflation: The Invisible Price Hikes
Manufacturers have mastered the art of the invisible price hike. The most common tactic is shrinkflation, where the package stays the same size but the amount of product inside decreases. That family-size bag of chips suddenly has 1.5 ounces less product for the same price. It’s like your favorite coffee shop slowly shrinking your “large” cup every month, hoping you won’t notice the difference.
It’s a deliberate strategy. A recent report from Consumer World found over 100 popular products had been downsized in the last year alone. Then there’s its insidious cousin, skimpflation. This is when companies secretly swap out higher-quality ingredients for cheaper alternatives to cut costs without changing the price tag. Your favorite ice cream might now use more artificial thickeners instead of real cream, or that “100% juice” now contains more pear juice concentrate — a cheap filler. Understanding these tactics is the first step in steering clear of financial traps.
Measuring Your True Purchasing Power
Forget the national average; you need to calculate your own inflation rate. Your purchasing power is the real measure of your financial health. So how can you track it? The simplest method is to compare your current grocery and utility bills to receipts from one or two years ago for the exact same items. The percentage increase you see is what matters to your budget.
This isn’t just an academic exercise. It’s about taking control.
By understanding exactly where your costs are rising, you can adjust your spending and investment strategies accordingly. Recognizing that your personal inflation on essentials is closer to 7% than the official 3% provides the critical context needed to build a personal financial compass that actually works. This awareness changes how you view sales, budgets, and even your own salary. The erosion is real, but it doesn’t have to be your reality.
Behavioral Biases: The Unseen Saboteurs of Frugal Intentions
You think your budget is failing because of external market forces? Think again. The most significant threat to your financial plan isn’t inflation or a volatile stock market; it’s the faulty wiring inside your own skull. While you track every dollar, a set of predictable, irrational behaviors are quietly draining your accounts. These aren’t personal failings. They are universal cognitive shortcuts that sabotage even the most disciplined savers.
What most people miss is that the psychology of spending is often more powerful than the logic of budgeting. You can build the perfect financial spreadsheet, but it’s useless if your brain is programmed to self-destruct. Understanding the behavioral science behind your financial decisions is the first step toward actually taking control.
The Allure of Instant Gratification: Overcoming Present Bias
Your brain is hardwired to prefer immediate rewards over future gains, a tendency behavioral economists call present bias. It’s the internal voice that screams “yes” to the expensive dinner out tonight instead of putting that same money into a retirement account that will compound for decades. This isn’t just a lack of willpower. It’s a cognitive glitch.
This bias explains the explosion of “buy now, pay later” services. They exploit our desire for immediate satisfaction by pushing the financial pain into the future. Research from the University of Chicago Booth School of Business suggests people are willing to sacrifice significant future value—sometimes as much as 30-50%—for a smaller, immediate reward. Why does waiting for a larger payoff feel so difficult? Because the future is abstract, but the satisfaction of a new purchase is concrete and immediate—that dopamine hit is a powerful, and expensive, feeling.
Mental Accounting: Why We Treat Money Differently
Here’s a question: why does a $200 tax refund feel like “free money” ripe for a splurge, while a $200 bonus at work feels like hard-earned cash to be saved? It’s the same amount of money, yet we assign it a different emotional value. This irrational behavior is called mental accounting, a process where we subconsciously categorize money into different buckets.
It’s like having separate mental jars for “vacation fund,” “bill money,” and “windfall cash.” The problem is, money is fungible; a dollar is a dollar, regardless of its source. Treating a tax refund or a small inheritance as “fun money” is one of the most common mistakes that can derail a frugal lifestyle. This compartmentalization prevents us from seeing our finances as a single, unified picture, leading to poor allocation of resources and missed opportunities for growth.
It’s a flawed system.
Overcoming Your Biases: A Smart Spending Checklist
Recognizing these biases is half the battle. Actively questioning your motivations before a purchase can help short-circuit these ingrained responses and align your spending with your actual goals. Before your next non-necessary purchase, run through this mental checklist.
Am I buying this for “future me” or “right now me”? This question directly confronts present bias by forcing you to consider long-term consequences.
If this money was part of my regular paycheck, would I still spend it this way? This helps break down the walls of mental accounting, particularly for windfalls like bonuses or gifts.
What is the “time cost” of this item? Calculate how many hours you had to work to afford it. Suddenly, that $150 gadget might seem less appealing when you realize it represents a full day’s labor.
Can I implement a 24-hour rule? For any non-urgent purchase over a set amount (say, $50), force yourself to wait a full day. This cooling-off period often extinguishes the emotional urgency created by present bias.
Is this purchase moving me closer to or further from my main financial goal? Comparing a small, immediate pleasure to a large, future ambition—like those detailed in real stories of frugal success—can provide powerful perspective.
This isn’t about depriving yourself; it’s about ensuring your spending is a conscious choice, not an unconscious reaction. The real challenge lies in building systems that act as a guardrail against your own worst impulses.
We are all influenced by the frames, the descriptions of the choices we face.
— Richard H. Thaler, Nobel Laureate in Economics
Service
Common Hidden Fees
Potential True Cost Increase
Budget Airline Ticket
Seat Selection ($22), Carry-On Bag ($45), Checked Bag ($38), In-Flight Wi-Fi ($8)
Supply Chain Secrets: How Global Disruptions Impact Your Local Budget
Most people think their budget is a local affair, determined by their salary and spending habits. That’s a dangerous oversimplification. The truth is your grocery bill is a direct reflection of global events, turning your weekly shopping into an unwilling participation in global economics. A single storm or political spat thousands of miles away can quietly add dollars to your receipt.
Consider the price of your morning coffee. When a severe frost hit Brazil’s coffee belt, it didn’t just affect farmers there. According to data from the International Coffee Organization, the resulting 30% drop in crop yield caused a 58% surge in the wholesale price of Arabica beans globally. This is how navigating economic currents becomes a daily necessity, not just an abstract concept for investors. That price hike is passed directly to you, the consumer, months later.
It’s a fragile chain of dominoes.
From microchips in your car to the cotton in your t-shirt, these invisible connections dictate consumer prices. A factory shutdown in Asia or a shipping container shortage in a major port creates scarcity, and scarcity inflates cost. What most people miss is that understanding this system isn’t just academic; it’s a critical tool for avoiding common financial traps. Recognizing these patterns allows you to anticipate price hikes and adjust your spending before they hit your bank account.
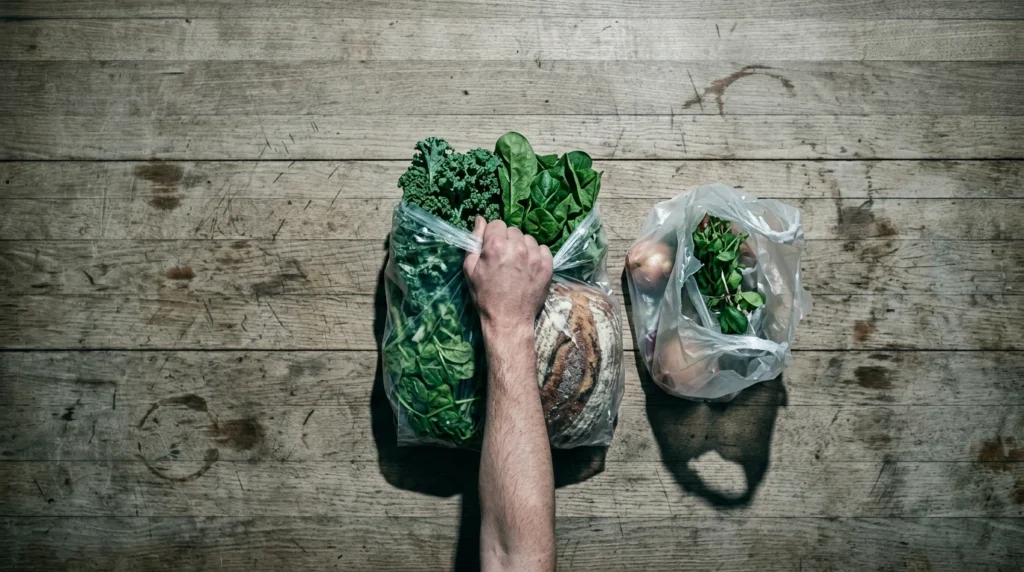
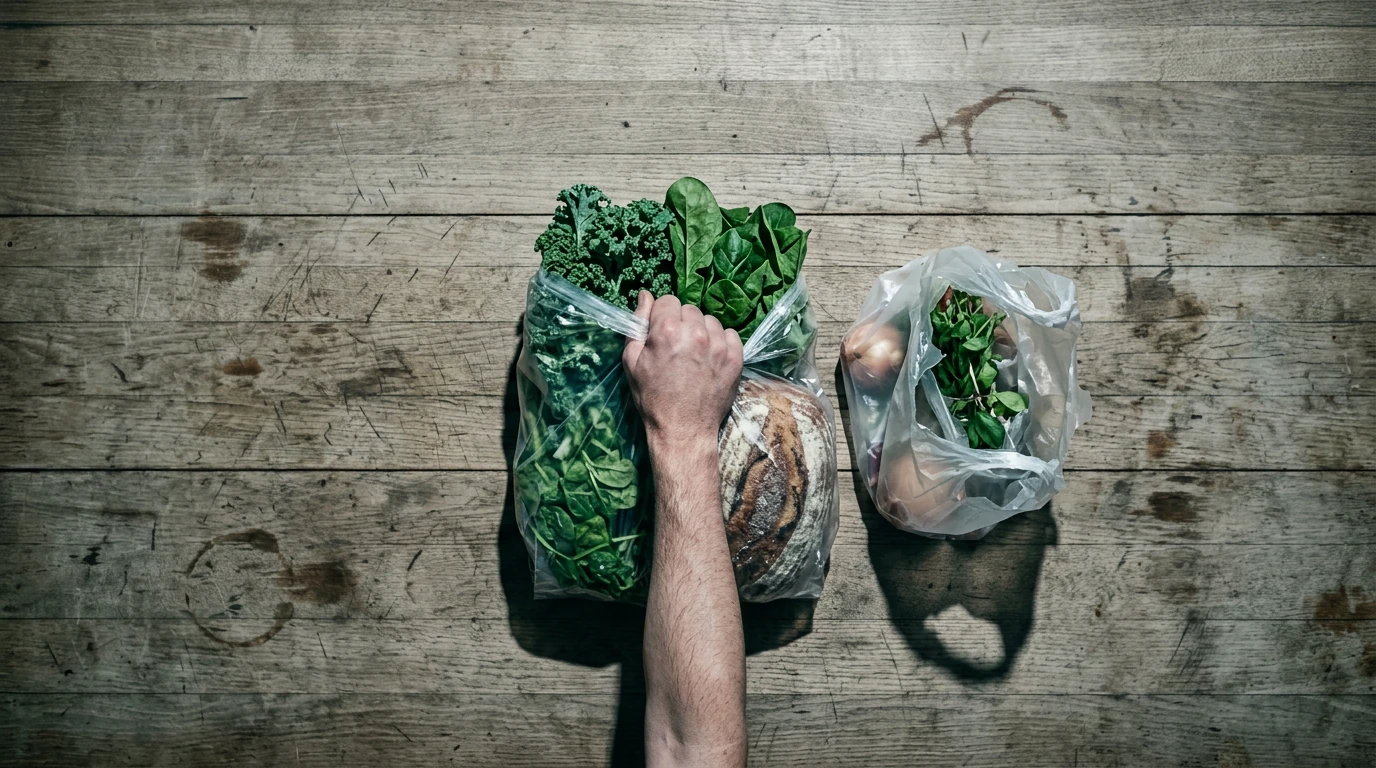
Overhead view of a person’s hand holding a full grocery bag next to a visibly smaller, less full bag, symbolizing inflation and shrinkflation eroding purchasing power on a weathered kitchen table.
The ‘Hidden Fees’ Phenomenon: Beyond the Obvious Price Tag
The price you see is almost never the price you pay. This isn’t an accident; it’s a core component of modern business strategy. Companies across industries have perfected the art of burying costs, counting on consumer apathy and the sheer complexity of service agreements to pad their bottom lines. They are betting you won’t notice. The underrated factor here is psychological fatigue—consumers are so bombarded with information that they surrender to the path of least resistance, which often means paying more.
This practice is a direct challenge to anyone aiming for financial discipline. It turns smart spending into a minefield where the advertised cost is just bait. What most people miss is that these fees are engineered to feel small and unavoidable, making them seem unworthy of a fight.
Deconstructing Service Charges: What You’re Really Paying For
From banking to travel, the initial price is merely an invitation to a more expensive party. A “free” checking account might come with out-of-network ATM fees, overdraft charges, and monthly maintenance costs if your balance dips below a certain threshold. That budget airline ticket looks great until you add fees for a carry-on bag, seat selection, and even printing your boarding pass at the airport. These are some of the most common financial traps to avoid.
Consider how these seemingly minor additions compound. What begins as a good deal quickly becomes more expensive than the “full-service” alternative you initially dismissed. Let’s look at a few common examples:
Service
Common Hidden Fees
Potential True Cost Increase
Budget Airline Ticket
Seat Selection ($22), Carry-On Bag ($45), Checked Bag ($38), In-Flight Wi-Fi ($8)
A more insidious version of the hidden fee is the subscription model. Each individual charge—for streaming services, software, news apps, or curated boxes—seems negligible. But together, they act like barnacles on the hull of your financial ship; individually tiny, but collectively creating immense drag. A recent analysis by WestMonroe Partners found that consumers underestimate their monthly subscription spend by an average of over 100%.
This is a deliberate exploitation of our cognitive biases, a core concept in the behavioral science of wealth. Companies know that once a recurring payment is authorized, it fades into the background noise of our bank statements. How many of us are paying for a service we signed up for with a free trial and simply forgot to cancel? The “set it and forget it” convenience is precisely the trap.
The only defense is a ruthless, manual audit of your bank and credit card statements. These recurring costs directly undermine long-term savings goals and represent a quiet drain on your financial future. The real question is no longer if you are paying for things you don’t use, but what you plan to do about it.
Investment Basics Revisited: The True Cost of Inaction and Over-Optimization
Most people think the biggest investment risk is losing money. They are wrong. The most corrosive, wealth-destroying risk is the one nobody talks about at dinner parties: the cost of doing nothing. That cash you have stashed in a savings account, earning a pathetic fraction of a percent, isn’t just sitting there safely. It’s actively shrinking in value every single day thanks to inflation.
This is the paralysis of the “safe” investor. It’s a mindset that confuses inactivity with prudence. The hard truth is that avoiding the market isn’t a neutral choice; it’s a guaranteed long-term loss.
The Silent Tax: Understanding Opportunity Cost in Your Portfolio
Opportunity cost is the ghost in your financial machine. It represents the potential gains you forfeit by choosing one option over another. Consider this: stashing $10,000 in a savings account earning 0.40% APY for a decade leaves you with about $10,408. Had you invested that same $10,000 in a simple S&P 500 index fund averaging a historical 7% annual return, that sum could have grown to over $19,670. That nearly $9,300 difference is the price you paid for “safety.”
What most people miss is that this isn’t just about missing out on bull markets. It’s about failing to outpace the slow, steady erosion of your purchasing power. Learning to recognize these hidden losses is a core part of building the frugal foresight needed for tomorrow’s wallet. The real question isn’t whether you can afford to invest, but can you afford not to?
Frictional Costs: When ‘Smart’ Investing Becomes Expensive
On the other end of the spectrum from inaction is the hyperactive trader. This investor believes they can outsmart the market by constantly buying and selling. This strategy is seductive, promising to catch every peak and dodge every valley. In reality, it’s often a fast track to self-sabotage through frictional costs.
These costs are the small, pesky charges that eat away at returns with every move you make. Think of it like constantly changing lanes in a traffic jam—you expend a lot of energy, create stress, and often end up no further ahead, or even behind. Frictional costs include trading commissions, bid-ask spreads, and, crucially, short-term capital gains taxes, which are often taxed at a higher rate than long-term gains. One study from UC Berkeley found that the most active traders underperformed the market by a staggering 6.5% annually, proving that more activity rarely equals better results.
The Power of Patience: Avoiding Costly Over-Optimization
The temptation to constantly tweak your portfolio — a behavior known as over-optimization — is a direct path to higher costs and lower returns. It stems from a desire for control in an inherently unpredictable system. Investors fall victim to “shiny object syndrome,” chasing the latest hot stock or complex strategy they read about online. This constant churn prevents your best assets from doing what they do best: compounding over time.
Dr. Eleanor Vance, a behavioral finance expert at the University of Chicago, puts it bluntly: “Compound interest is the engine of wealth creation, but patience is the fuel. Every time you interrupt it by selling too soon or chasing a fad, you’re essentially restarting that engine from cold.” The underrated factor here is understanding the behavioral science of wealth and recognizing that your own impulses are often your worst enemy.
Minimizing Fees for Maximizing Returns
The single most effective way to protect your long-term growth is to become obsessed with minimizing fees. A seemingly tiny 1% annual management fee doesn’t sound like much, but its impact is devastating over time. A report from the Department of Labor revealed that a 1% fee can reduce your final retirement balance by nearly 28% over a 35-year investment horizon. That’s hundreds of thousands of dollars vanished for no good reason.
To combat this, prioritize low-cost index funds or ETFs over actively managed funds with high expense ratios. Scrutinize every platform fee and advisory charge. The goal isn’t just to make money; it’s to keep as much of it as possible working for you, not for a fund manager.
The Environmental Price Tag: Sustainable Spending’s Overlooked Financial Edge
The sticker price is a lie. That cheap t-shirt or disposable gadget carries a hidden invoice, one paid through environmental degradation and, eventually, your own bank account. What most people miss is that the true cost of a product includes its entire lifecycle—from creation to disposal. According to the U.S. Environmental Protection Agency, landfills received 27 million tons of plastics in a recent year, and managing that waste costs taxpayers dearly.
This is where sustainable spending reveals its financial power. Choosing a durable, repairable item over a cheap, disposable one helps you avoid common financial traps linked to constant replacement. The long-term savings are significant.
Of course, the upfront cost of sustainable goods can feel prohibitive. But is a $150 pair of boots that lasts a decade more expensive than a $40 pair you replace every single year? The math is simple, yet the behavioral science of our spending choices often leads us astray, chasing the immediate bargain. It is a classic case of being penny-wise and pound-foolish.
Shifting your mindset from short-term cost to long-term value is about building financial resilience in a world where resources are becoming more expensive, a key part of understanding tomorrow’s wallet and its economic currents. The most frugal choice is often the one you only have to make once.
Beyond Defense: Architecting Your Personal Economy
Now that you can see the hidden fees, the psychological traps, and the invisible economic levers at play, the challenge shifts. Moving forward, it’s not enough to simply play defense by avoiding fees or spotting smaller packages. The real question is what this new awareness demands of your financial identity. Are you content to remain a consumer, reacting to the market’s manipulations, or are you ready to become the active manager of your own personal economy? This shift in perspective—from reactive saving to proactive value creation—is the ultimate tool for building lasting wealth in a system designed to obscure the true cost of everything.
Frequently Asked Questions
How does ‘shrinkflation’ impact my monthly budget?
Shrinkflation directly increases your expenses by giving you less product for the same price. This means you run out of items like snacks, cereal, or toilet paper sooner, forcing you to purchase them more frequently and driving up your total monthly spending on essentials.
What are the most common behavioral biases affecting my spending habits?
Two of the most common are ‘present bias,’ which prioritizes immediate rewards over long-term goals like saving, and ‘mental accounting,’ which causes you to treat windfalls like a tax refund as ‘free money’ for splurging. These biases encourage impulsive buys and undermine disciplined financial planning.
Can global supply chain issues really affect the price of my groceries?
Absolutely. A drought in a coffee-growing region, a shipping container shortage, or a factory shutdown overseas can create scarcity and increase transportation costs. These expenses are passed down the chain, directly resulting in higher prices for goods like coffee, electronics, and even basic produce at your local store.
How can I identify and avoid hidden fees in services and subscriptions?
The best defense is a proactive audit. Always read the fine print before signing up for anything and regularly review your credit card and bank statements for recurring charges. Use comparison tools for travel and banking to see the ‘all-in’ cost, not just the advertised price.
What is the ‘cost of inaction’ in investment basics?
The cost of inaction is the potential growth you lose by keeping your money in cash or low-yield savings accounts instead of investing it. While it feels safe, your money’s purchasing power is actively eroded by inflation, meaning you are guaranteed a long-term loss of value by doing nothing.
Does sustainable spending save money in the long run?
Yes, it often does. While some sustainable products have a higher initial cost, they can lead to significant long-term savings. For instance, energy-efficient appliances lower your utility bills, and durable, well-made goods need to be replaced far less often, reducing your overall consumption and expenses over time.
Matheus Neiva has a degree in Communication and a specialization in Digital Marketing. Working as a writer, he dedicates himself to researching and creating informative content, always seeking to convey information clearly and accurately to the public.