Eco-Conscious Savings: Pioneering Budget Strategies for Sustainable Living
Discover how sustainable living is no longer a luxury but a powerful strategy for financial freedom. This guide provides actionable tips on budgeting, circular economy principles, and home efficiency to help you save money while protecting the planet.
By: Matheus Neiva on October 26, 2026
Does it ever feel like your budget has a slow, constant leak you just can’t find? You track expenses and cut back, yet money seems to vanish. The culprit is often hidden in plain sight, disguised as convenience: the disposable coffee cups, the cheap appliances that break in a year, the bag of groceries that wilts in the fridge. This cycle of “take, make, and waste” isn’t just an environmental problem; it’s a direct and continuous drain on your personal finances.
For too long, sustainable living has been marketed as a luxury—an expensive choice reserved for those with ample disposable income. This perception is not only outdated, it’s fundamentally incorrect. The core principles of an eco-conscious lifestyle, such as reducing waste, prioritizing durability, and conserving resources, are perfectly aligned with the goals of smart financial management. Adopting these habits is less about sacrifice and more about strategic efficiency, plugging those invisible financial leaks for good.
This shift in mindset redefines what it means to be frugal in the modern economy. In this guide, we will move beyond generic advice and explore practical, pioneering strategies that merge ecological responsibility with financial prudence. You’ll discover innovative budgeting frameworks that track impact, learn how to leverage the circular economy to cut costs on major purchases, and implement low-cost home efficiency hacks that deliver immediate savings. It’s time to build a budget that not only secures your financial future but also invests in a healthier planet.
The Evolving Landscape of Sustainable Living and Personal Finance
The conversation around sustainability has fundamentally shifted. It’s no longer a luxury reserved for the affluent but has become a powerful strategy for anyone looking to optimize their personal finances. Thinking green is now a form of rebellion against disposable culture and its associated expenses, forcing us to re-evaluate our spending habits through the lens of advanced economic trends. The data suggests a surprising convergence between ecological responsibility and financial prudence.
A recent consumer report from the Global Sustainability Study revealed that while 71% of consumers are willing to pay a premium for sustainable brands, the underrated factor here is the total cost of ownership. What if the higher upfront cost of an energy-efficient appliance or a durable piece of clothing actually saves you more money over its lifespan? This market shift—where longevity and efficiency are becoming key selling points—is quietly unmasking the invisible costs of cheap, disposable alternatives.
This changes the entire budgeting equation.
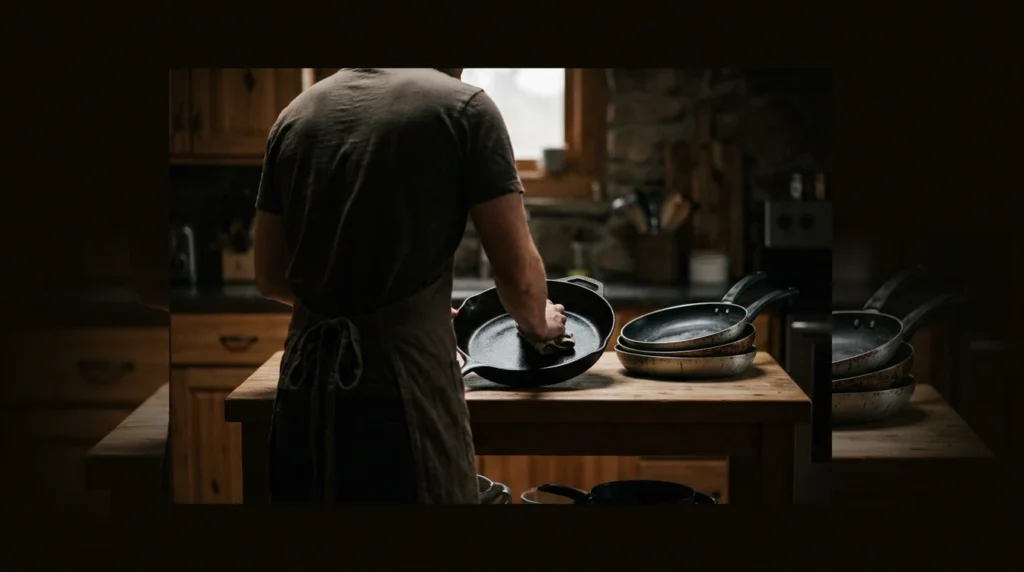
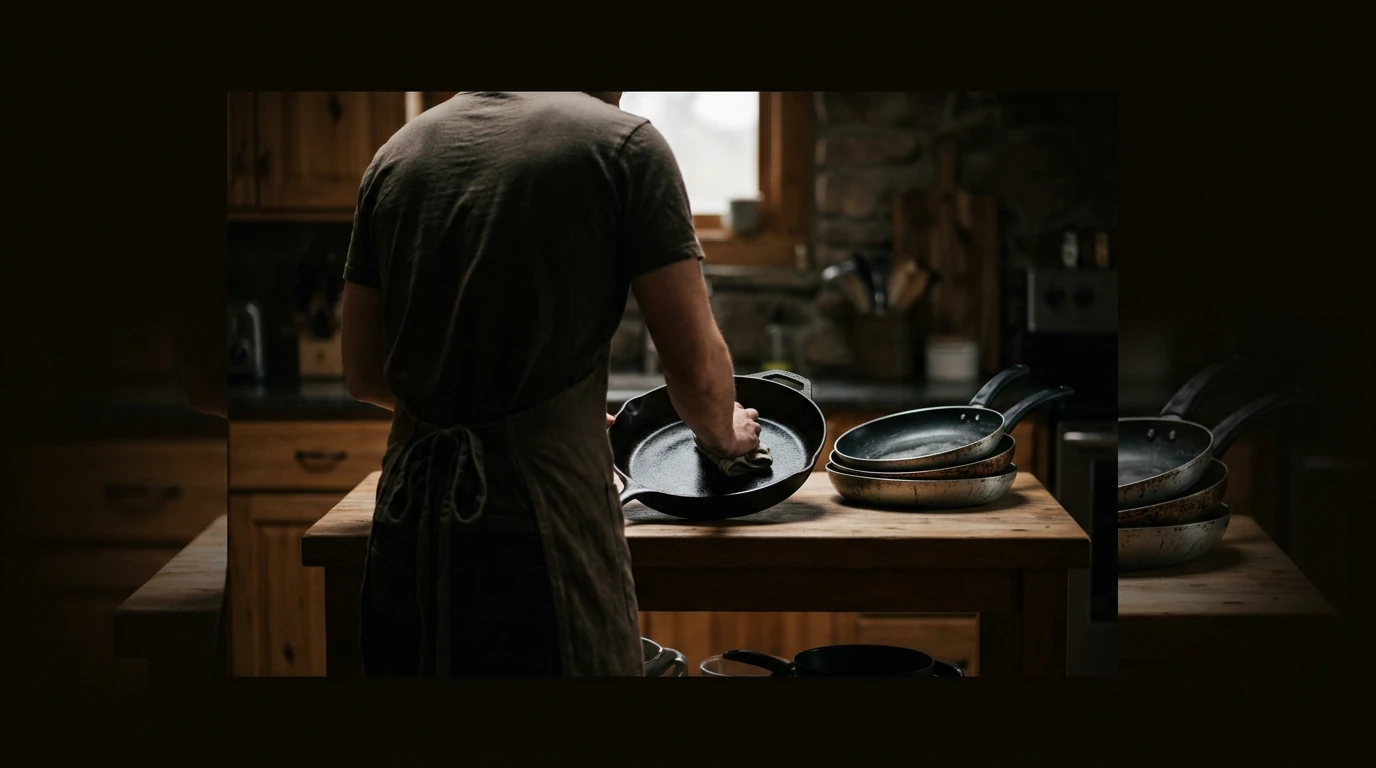
Adopting an eco-conscious mindset is less about sacrifice and more about strategic investment. It’s like choosing to buy a quality cast-iron skillet once instead of replacing a cheap, non-stick pan every couple of years. The initial expense is higher, but the long-term savings are undeniable (and your food will probably taste better, too). This approach redefines what it means to be frugal in the modern economy.
Ultimately, the line between saving the planet and saving your money is becoming increasingly blurred. Understanding this connection is primary for anyone serious about navigating future economic currents and building lasting financial resilience.
Innovative Budgeting Frameworks for a Green Lifestyle
Most popular budgeting advice is fundamentally broken for anyone serious about sustainability. The classic 50/30/20 rule, for instance, only measures where your money goes, not the value it creates or the impact it leaves behind. It’s like judging a car’s performance solely on its mileage per gallon while completely ignoring engine wear, maintenance costs, and emissions. A budget focused on sustainable living budget tips requires a total paradigm shift from simple expense tracking to a more holistic lifecycle costing.
This new approach starts by reframing your spending categories. Instead of a generic “Transportation” line item, you might create a “Sustainable Mobility” category that includes public transit passes, bicycle maintenance, and maybe even a sinking fund for an electric vehicle. The point is to create buckets that force you to weigh the long-term financial and environmental benefits of your choices. This isn’t just about spending less; it’s about understanding the invisible costs hidden within conventional consumption patterns.
Beyond Zero-Waste: Investing in Durability and Repair
A eco-conscious budget prioritizes investment over expenditure, especially regarding consumer goods. It actively rejects the “buy cheap, buy twice” cycle that plagues modern finances. For example, purchasing a $300 pair of well-made, repairable boots instead of five pairs of $60 fast-fashion alternatives over the same period represents a clear financial win. A recent analysis from the Boston Consulting Group suggests consumers can save up to 22% over five years by opting for durable, repairable goods over their disposable counterparts.
This strategy is about calculated acquisition, not deprivation.
Building a small, dedicated “Repair & Maintenance” fund into your monthly budget is a powerful move. It transforms you from a passive consumer into an active owner of your possessions. What most people miss is how this small change in financial planning can completely alter your relationship with material goods — you start seeing value in upkeep, not just in the thrill of a new purchase. It’s a subtle but significant way to avoid some of the most common mistakes in frugal living.
Digital Tools and Apps for Tracking Eco-Financial Impact
Technology is finally catching up to this mindset, offering tools that connect your spending directly to your carbon footprint. Apps are now available that sync with your bank accounts to automatically calculate the environmental impact of each transaction. But do these digital nudges actually work? The data suggests they do. One report from fintech analyst firm Forrester Research found that users who actively track their spending’s carbon impact reduce their non-primary spending by an average of 9% within the first six months.
Seeing a carbon score next to your morning coffee purchase provides a powerful data point that a simple dollar amount lacks. It taps into the behavioral science behind our spending decisions, making the abstract consequences of consumption tangible and immediate. The next frontier for these tools isn’t just tracking past behavior but projecting the long-term financial and environmental savings of future choices, merging your wallet with your values.
We don’t need a handful of people doing zero waste perfectly. We need millions of people doing it imperfectly.
— Anne-Marie Bonneau, Zero-Waste Chef
Strategy Area
Key Actionable Tip
Budgeting Framework
Prioritize durable, repairable goods over cheap, disposable alternatives to lower long-term replacement costs.
Circular Economy
Use sharing platforms and tool libraries for infrequently used items to gain access without the cost of ownership.
Home Energy Efficiency
Install smart power strips to automatically cut off “vampire power” drawn by electronics on standby.
Food Consumption
Implement weekly meal planning to buy only what you need, drastically cutting the average $1,600 in annual food waste.
Smart Consumption: Cutting Costs with Circular Economy Principles
The modern economy is built on a lie: that you must constantly buy new things. This “take-make-waste” model is not just an environmental disaster; it’s a deliberate drain on your bank account. A circular economy flips this script entirely. Instead of a straight line to the landfill, it creates a loop where resources are reused, repaired, and repurposed, keeping value in your pocket. The data suggests—though not conclusively—that households embracing these principles can reduce their spending on consumer goods by up to 25% annually, according to analysis by the Sitra institute.
This isn’t about deprivation. It’s about optimization. By shifting your mindset from a consumer to a custodian of resources, you actively reject planned obsolescence and start building real wealth. It’s a core change in how you view “stuff.”
The Resurgence of Repair Culture: DIY vs. Professional Services
Before you toss that sputtering coffee maker or cracked smartphone, stop. The “right to repair” movement is gaining serious momentum, and it’s your ticket to significant savings. Your first decision point is whether to do it yourself or hire a professional. For simple fixes like replacing a fuse or a button, online tutorials have made DIY repairs more accessible than ever, often costing just a few dollars for parts.
But what most people miss is the risk calculation. Is spending $85 to professionally fix a seven-year-old washing machine worth it when a new one is $600? Almost always, yes. The key is to weigh the repair cost against the replacement cost. A botched DIY job on a complex electronic device can turn a simple fix into a total loss, highlighting one of the key common mistakes in frugal living. As a rule of thumb, if a professional repair costs less than 50% of a new item, it’s a sound financial decision.
Leveraging the Sharing Economy for Big Savings
Why own a lawnmower you use six times a year? The sharing economy challenges the very notion of ownership, proposing a more efficient model: access over assets. This goes far beyond ride-sharing apps. Think about tool libraries, peer-to-peer RV rentals, and high-end clothing subscription services. You get the utility of the item without the massive upfront cost, insurance, maintenance, or storage headaches — (and let’s be honest, you get to reclaim your garage space from things you rarely touch).
This model is a core component of navigating future economic currents with financial foresight. It forces you to pay only for what you actually use.
Community Swaps and Barter Systems
One of the most direct ways to participate in the circular economy is by cutting out the middleman entirely. Local community swap events and online bartering platforms allow you to trade items you no longer need for things you do. Think children’s clothing, books, kitchen gadgets, or even services like babysitting for yard work. This creates a hyper-local, cash-free economy that strengthens community ties while keeping perfectly good items in circulation. It’s less like a formal transaction and more like a neighborhood-wide collaboration.
Subscription vs. Ownership: A Cost-Benefit Analysis
The subscription model is expanding into nearly every product category, from cars to furniture. The financial logic can be compelling, but it requires careful analysis. Owning a car, for instance, involves the sticker price plus a cascade of other expenses. There’s insurance, registration, depreciation, and unexpected repairs, all of which represent the unmasking of invisible costs that drain your budget over time.
A car subscription service, conversely, might bundle these into a single monthly fee. For example, a service like Subscribe might charge $550 per month for a sedan, all-inclusive. Buying that same $30,000 car could involve a $520 monthly payment (on a 60-month loan), plus an average of $150 for insurance and $80 for monthly maintenance and repair savings. The subscription is initially more expensive on paper, but it eliminates volatility and the catastrophic financial hit of a major repair. The choice depends entirely on your tolerance for risk and need for predictability.
A person polishing a cast-iron skillet on a rustic kitchen island, symbolizing durable, eco-conscious investing over disposable alternatives, with dramatic lighting.
Greening Your Home: Energy, Water, and Waste Efficiency on a Budget
Most people think a sustainable home requires solar panels and a five-figure investment. This is a comforting myth that lets you off the hook. The truth is your home is probably leaking money through dozens of small inefficiencies, and fixing them costs less than a few takeout dinners. What most people miss is that true financial control starts by plugging these almost invisible drains on your resources. These are the unseen costs that erode your budget month after month.
Stop blaming the utility company for high bills. Your habits are likely the real problem.
Low-Cost Energy-Saving Hacks
Your electronics are costing you money even when they’re turned off. This phenomenon, often called vampire power, involves devices drawing electricity on standby mode. According to the U.S. Department of Energy, this phantom load can account for as much as 10% of a household’s annual electricity use. The simplest solution is using smart power strips that automatically cut power to devices not in active use — a one-time purchase that pays for itself quickly. It’s a simple fix.
Beyond gadgets, your home’s physical envelope is another battleground for savings. Ignoring drafts around windows and doors is like trying to fill a bucket with a hole in it. A few dollars spent on weatherstripping and caulk can yield significant returns by reducing heating and cooling loads. Are you really using that guest room all winter? Sealing the vent and closing the door creates a thermal buffer, preventing wasted energy on an unused space.
Water Conservation Without Sacrificing Comfort
The idea of a water-saving showerhead often brings to mind a weak, unsatisfying trickle. That’s an outdated assumption. Modern, low-flow faucet aerators and showerheads can reduce water consumption by 30% or more without a noticeable drop in pressure, thanks to better engineering that mixes air with the water stream. For less than $20, you can cut your water heating costs — the second-largest energy expense in many homes — and lower your water bill simultaneously.
Of course, the most significant waste often comes from neglect. That tiny drip from the kitchen faucet might seem insignificant, but a single faucet dripping at one drop per second can waste over 3,000 gallons per year. That’s enough water for more than 180 showers. Ignoring such a simple repair is one of the classic frugal living mistakes that people make without even realizing the cumulative financial impact.
Here is a simple checklist for immediate action:
Seal the leaks: Apply weatherstripping to doors and windows and caulk any visible gaps.
Tackle vampire power: Unplug chargers when not in use or connect electronics to a smart power strip.
Upgrade your aerators: Install low-flow aerators on kitchen and bathroom faucets.
Fix dripping faucets: Replace worn-out washers to stop leaks and prevent massive water waste over time.
These adjustments aren’t about sacrifice; they are about efficiency. Each small change acts like an automatic savings deposit into your account, compounding financial benefits for years to come.
Conscious Food Choices: Nourishing Your Wallet and the Planet
Most people treat their grocery budget like a leaky bucket, pouring money in while completely ignoring the gaping holes. The biggest hole is food waste. It’s a quiet financial disaster happening in your refrigerator every week. The USDA’s Economic Research Service reports that the average American family of four discards approximately $1,600 worth of food annually, with produce being the primary culprit. This isn’t just an environmental issue; it’s a symptom of poor financial planning.
Strategic meal planning is the single most effective defense. By mapping out meals, you buy only what you need, sidestepping the impulse buys that lead to spoiled food and what many consider common financial traps. Think about it—would you build a house without a blueprint? Why approach your weekly food consumption any differently? This simple discipline reclaims a significant portion of that wasted cash.
Shifting toward more plant-based meals offers another powerful lever for savings. The underrated factor here is the raw cost difference. A pound of lentils can cost under two dollars, while a pound of ground beef often exceeds six dollars. This choice alone — even just a few times a week — compounds into substantial savings over a year. It’s a direct vote for both your wallet and a less resource-intensive food system.
Buying local and seasonal produce further tightens your budget by cutting out the costs of long-distance transportation and storage. Exploring these options is a core part of a comparative guide to smarter spending. The future of frugal living won’t just be about clipping coupons; it will be about understanding and shortening the distance from farm to table.
The Future of Frugality: Adapting to New Green Economic Shifts
The very definition of being frugal is changing. What was once a simple game of clipping coupons and buying in bulk is now intricately linked to global resource management and energy markets. Adapting your budget for sustainability is no longer a niche hobby for environmentalists; it is becoming a core strategy for financial survival and growth. The data suggests that households that ignore these shifts may face significant cost pressures in the coming decade. This is where tomorrow’s wallet is being shaped today.
Emerging Technologies Driving Eco-Efficiency and Savings
Technological advancements are making it easier and cheaper to live sustainably. Think of smart home devices that optimize energy consumption without you lifting a finger—it’s like having a tiny, hyper-efficient accountant managing your utility bills. For instance, the U.S. Department of Energy reports that a programmable or smart thermostat can reduce annual heating and cooling costs by about 8%. That might not sound like much, but it compounds over years.
These systems learn your household’s patterns, adjusting temperature settings automatically for when you’re away or asleep. Similar gains are found in smart lighting, energy-efficient appliances, and even water heaters that only operate during off-peak hours. The underrated factor here is the passive nature of the savings; once installed, the technology does the work for you.
Policy Changes and Incentives for Green Living
Governments are increasingly using financial incentives to nudge consumers toward greener choices. These policies recognize that individual action, when aggregated, can have a substantial economic and environmental impact. What most people miss is that these aren’t just handouts; they are strategic investments designed to accelerate the transition to a less volatile, more efficient economy. These programs essentially lower the barrier to entry for making long-term, cost-saving upgrades to your home and lifestyle.
Tax Credits and Rebates for Sustainable Upgrades
One of the most direct ways policy impacts personal finance is through tax credits and rebates. For example, federal programs frequently offer substantial tax credits—sometimes as high as 30%—for installing high-efficiency heat pumps, solar panels, or even upgrading home insulation. A homeowner spending $9,000 on a new heat pump system could potentially see a $2,700 reduction in their tax liability.
Ignoring these opportunities is a common and costly error. You can often find state and local utility companies offering additional cash rebates for purchasing Energy Star-certified appliances or recycling old, inefficient ones. Staying informed about these programs is a critical component of modern, strategic spending.
Building a Resilient Personal Economy Through Sustainable Choices
Ultimately, integrating these practices is about building a more resilient personal financial structure. By reducing reliance on fluctuating energy prices and resource-intensive goods, you insulate your budget from market shocks. How much would a sudden 40% spike in natural gas prices affect your winter heating bill? For a household with a geothermal heat pump and upgraded insulation, the impact is significantly muted.
Dr. Alan Reed, an economist at the Center for Economic Policy and Research, explains that “households actively decoupling their required expenses from fossil fuel volatility are essentially creating a personal hedge against inflation and geopolitical instability.” This isn’t about predicting the future; it’s about building a financial lifeboat. The principles behind these choices are central to any sustainable investment strategy, creating a foundation that is less susceptible to the whims of unpredictable global markets and is explored in advanced economic trends analysis.
Beyond the Budget: Redefining Financial Resilience
Ultimately, adopting these sustainable budgeting strategies does more than just lower your monthly bills or reduce your carbon footprint. It fundamentally alters your relationship with the economy itself. By consciously choosing repair over replacement, access over ownership, and efficiency over convenience, you reclaim a degree of power from a system designed to keep you constantly consuming. This isn’t just about saving money; it’s about building a more resilient and independent financial life, one that is less vulnerable to market volatility and planned obsolescence.
As you integrate these practices, the focus shifts from a mindset of scarcity and sacrifice to one of resourcefulness and optimization. The skills you build—from mending a shirt to planning a zero-waste meal—become assets that pay dividends for a lifetime. With that in mind, what does true wealth look like to you? Is it an ever-growing bank account, or is it the freedom and capability to live well with less?
Frequently Asked Questions
How can I start sustainable living on a very tight budget?
Start with actions that are free or have an immediate payback. Focus on reducing food waste through meticulous meal planning, mending clothes you already own, and fixing minor leaks at home. Utilize community resources like libraries for books and entertainment, and look for local swap events to trade items instead of buying new.
What are the biggest financial benefits of adopting a sustainable lifestyle?
The primary financial benefits include significantly lower utility bills from energy and water conservation, reduced spending on groceries by minimizing food waste, and long-term savings from buying durable, repairable products instead of disposable ones. These combined savings increase your monthly cash flow and build financial resilience.
Are eco-friendly products always more expensive?
Not necessarily. While some items like energy-efficient appliances may have a higher initial cost, they save you money over their lifespan through lower operating costs. Many sustainable habits, such as making your own cleaning supplies, reducing consumption, or borrowing items, are inherently cheaper than conventional alternatives.
How can I track my environmental impact and savings simultaneously?
Several modern budgeting apps now offer features to estimate the carbon footprint of your purchases alongside your spending. For a manual approach, you can track your utility bills before and after making efficiency upgrades. You can also log ‘avoided costs’ each time you repair an item instead of replacing it to see your savings add up.
What is the role of the sharing economy in sustainable budgeting?
The sharing economy plays a important role by providing affordable access to goods and services without the high cost of ownership. Using tool libraries, car-sharing services, or clothing rental platforms allows you to pay only for what you use, drastically cutting expenses for items you don’t need every day and reducing overall production demand.
Matheus Neiva has a degree in Communication and a specialization in Digital Marketing. Working as a writer, he dedicates himself to researching and creating informative content, always seeking to convey information clearly and accurately to the public.